On this page
Key takeaways
- Tell the insurer. A will in a drawer is not notice.
- A trust nomination beats a later will. You need consent to undo the trust.
- A revocable nomination can lose to a later will the insurer has.
- No nomination and no will: up to S$150,000 under section 150.
The numbers
- Trust versus a later will
- The will does not revoke the trust
- Revocable versus a later will
- The will can replace it, if the insurer knows
- No form and no will
- Up to S$150,000 to a proper claimant
- Above that cap
- Letters of administration
- Muslim estates
- Not distributed under the Intestate Succession Act
The short answer
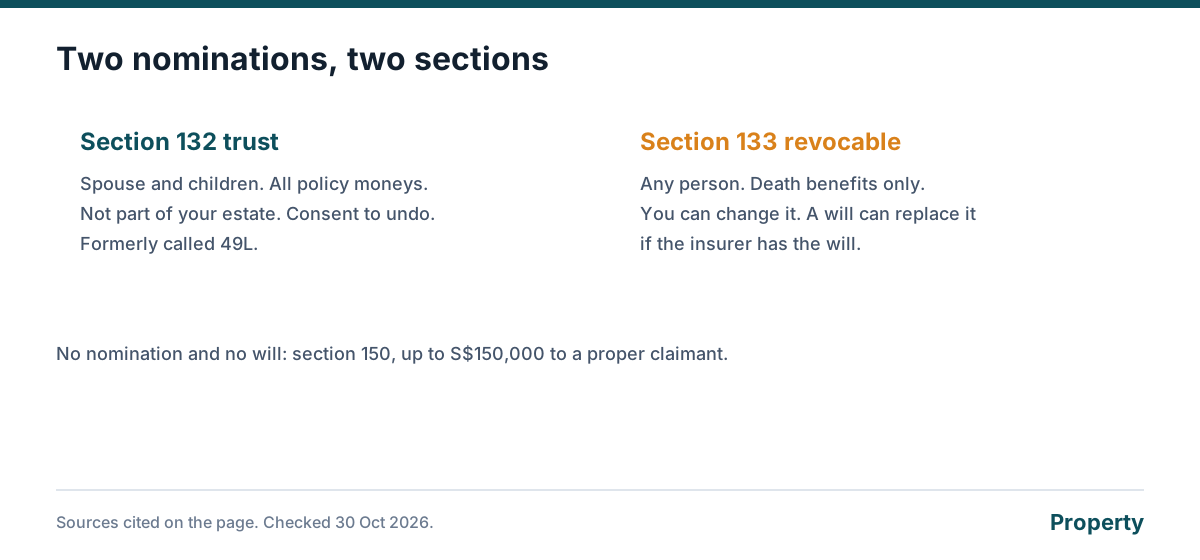
A will and an insurance nomination answer the same family question and they do not automatically agree. The insurer pays the policy on the instrument it knows about, under the Act. A trust nomination under section 132 takes the policy moneys out of your estate. A later will does not pull them back. You need the consent section 132 requires. A revocable nomination under section 133 is different. LIA’s 2026 guide says a will can replace it when the will disposes of all the death benefits, identifies the policy, and the insurer has been told.
If you have neither a nomination nor a will, section 150 allows the insurer to pay up to S$150,000 to a proper claimant. Anything above that waits for letters of administration. A large policy and silence is an expensive combination.
Tell the insurer, or the will is a private letter
LIA’s practical line is that if there is no nomination but there is a will, and the insurer has the certified copy, the proceeds can follow the will. The certified copy is the step families skip. The original in a safe at home does not update the insurer’s file. For a revocable nomination, the guide says the insurer pays the latest properly executed instrument it knows about, will or form.
| What exists | What the insurer can do |
|---|---|
| Trust nomination | Pay under the trust. A later will does not revoke it |
| Revocable nomination, and no later will on file | Pay the nominees the death benefit |
| Revocable nomination, then a will the insurer has, dealing with the whole death benefit | The will can replace the nomination |
| Will, no nomination, insurer notified | Pay according to the will |
| Nothing | Up to S$150,000 to a proper claimant. The rest needs an administrator |
The rest of the estate is still the will’s job
The nomination does not pass the flat, the car, or a bank account. CPF LIFE and CPF savings follow CPF’s own rules, and LIA says CPF retirement-sum annuities cannot be nominated under these sections at all. Integrated Shield and CareShield supplements should not be trust-nominated, because the claim is supposed to pay for your care. The trust page and the revocable page are the forms. The how-to page is the witnesses and the 100% rule. The hub is the index.
Muslim estates are outside the Intestate Succession Act. LIA points to the Syariah Court certificate and still says nominations can be made. That is a reason to get advice, not a reason this page can draft the certificate. We are not lawyers.
Send me quotes for these figures
What you need before a quote
- Flat type, or condo and floor area
- What the contents would cost to replace
- What the renovation cost
- Age of the building, if you care about seepage tracing
- Whether you live there or rent it out
Other ways to compare in Singapore
- compareFIRST, the life-insurance shelf MoneySense points to. Direct Purchase plans there are commission-free up to the published cap.
- The insurer's own site, if you already know the product and want its illustration.
- A licensed insurance broker you choose. We do not name one and we do not publish a phone number for one.
- A bank that distributes the policy, if that is where you bank. Ask them what they are paid. We do not list a rate.
- The calculators on this site, which show a result before you send a form.
Questions on this topic
I wrote a will after the nomination. Which wins?
If the nomination was a trust, the will does not undo it. If it was revocable, LIA says a will that deals with all the death benefits and names the policy can replace it, once the insurer has the will.
What is a proper claimant?
Section 150's phrase for a person the insurer may pay when there is no nomination, up to S$150,000. It is not a plan. The rest of a larger policy waits for an administrator if there is also no will.
Does the nomination cover my flat?
No. A nomination pays the policy. The flat, the bank account and the CPF balances follow their own rules. A will is still how you deal with those.
I am Muslim. Does the Intestate Succession Act apply?
LIA says it does not. Distribution of the estate follows the inheritance certificate from the Syariah Court. You can still make these nominations. Get advice on how they sit with that certificate.
Is it free?
Yes. The calculators and guides are free. A result appears in your browser before anyone asks for a phone number. Sending the form, if you want quotes for those figures, does not add a fee on this website.
Will you call me?
Not because you opened a page. We contact you only if you send the form or message us. You can read every result with the form left blank.
How does this site work?
The page does the arithmetic in your browser from the rules and the numbers you type. If you ask for quotes, we use your name, number and those figures only to reply about that enquiry. We do not sell the list. Personal data is handled under Singapore's Personal Data Protection Act. We are not an insurer and this is not financial advice.
Get a personalised breakdown
The calculator above runs in the browser with no phone number. Leave your details only if you want quotes or an audit for the same figures.
Sources
Facts on this page were checked against these sources on 30 October 2026.
- LIA: Your Guide to the Nomination of Insurance Nominees, 2026 lia.org.sg, checked 30 October 2026
- Insurance Act 1966, section 132 sso.agc.gov.sg, checked 30 October 2026
- Insurance Act 1966, section 133 and the nomination provisions sso.agc.gov.sg, checked 30 October 2026
Fact-checked against HDB, IRAS, CPF, MAS.
