Key takeaways
- Same product family as disability income, not a second invention.
- The deferred period is unpaid.
- A partial return to work can cut the benefit.
- Savings, not the insurer, cover the wait.
The numbers
- Benefit
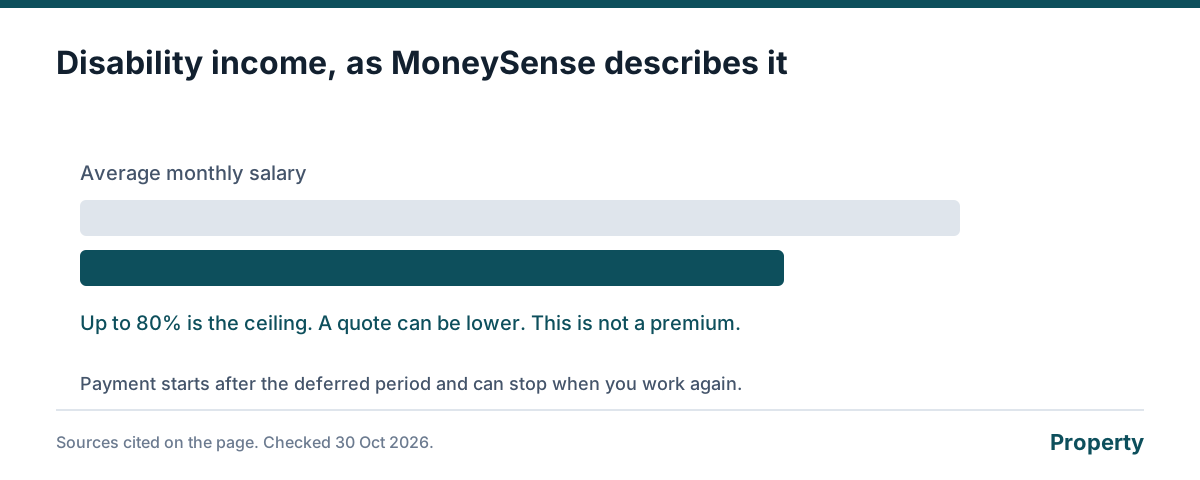
- Up to 80% of average monthly salary
- Before that
- The deferred period, unpaid
- Partial work
- Benefit may reduce in proportion
- Length
- Often 5 or 10 years, or to 60 or 65
- Not included
- A personal accident lump sum for illness
The short answer
Income protection insurance, in the way Singapore buyers use the words, is disability income cover. MoneySense describes one product for “replace your income when you are disabled and unable to work”, and the description is a monthly benefit of up to 80% of average salary, after a deferred period, for a limited number of years or until 60 or 65. If a quote uses the words income protection for a personal accident schedule, it is a different contract. Ask.
The part this page adds is the unpaid stretch. The insurer’s job starts when the deferred period ends and you are still disabled. Until then the loss is yours.
Build the wait into the plan
Write down the deferred period on the quote. Multiply it by the spending that does not stop: housing, food, the people who depend on the salary. That product is the cash you need somewhere else, in savings or in a spouse’s income. The insurance premium does not fill it. A shorter wait costs more and reduces that pile. A longer wait does the opposite. Neither is free.
When you return part-time, MoneySense says the benefit may reduce in proportion to recovery. A policy that pays the full 80% until you are back full-time is a different wording from one that tapers. Get that sentence in writing. We will not call one of them standard.
| Month of the claim | Who pays |
|---|---|
| During the deferred period | You. The policy is silent on purpose |
| After the wait, if you still meet the definition | The insurer, up to the benefit you were issued |
| If you work part-time | Often a reduced benefit. Read the proportion |
| If you can do the job in the definition again | The benefit stops |
| If the benefit period ends at 65, or after 5 years | It stops even if you are not well |
Do not double-count the MAS multiple
A term policy sized at 9 times income is a lump sum for the family if you die or meet that policy’s TPD test. It is not a salary for a two-year illness that never becomes TPD. Holding both can be coherent. Treating the lump sum as the income plan spends it on the mortgage and leaves the grocery years empty. The TPD comparison is that split. The disability income page is the 80% ceiling itself. The hub links the accident lump sum as well. We are not an insurer.
Send me quotes for these figures
What you need before a quote
- Flat type, or condo and floor area
- What the contents would cost to replace
- What the renovation cost
- Age of the building, if you care about seepage tracing
- Whether you live there or rent it out
Other ways to compare in Singapore
- compareFIRST, the life-insurance shelf MoneySense points to. Direct Purchase plans there are commission-free up to the published cap.
- The insurer's own site, if you already know the product and want its illustration.
- A licensed insurance broker you choose. We do not name one and we do not publish a phone number for one.
- A bank that distributes the policy, if that is where you bank. Ask them what they are paid. We do not list a rate.
- The calculators on this site, which show a result before you send a form.
Questions on this topic
Is income protection different from disability income?
In MoneySense's health-insurance list, the product that replaces income when you cannot work is disability income insurance. If a brochure says income protection, ask whether it is that contract or a personal accident plan with a weekly benefit.
How big should the emergency fund be?
At least the deferred period times your spending, because the policy pays nothing then. We will not turn that into a universal number of months.
What if I can work two days a week?
MoneySense says the payment can reduce in proportion to recovery. A partial return is not automatically a full benefit.
Does the MAS 9 times rule apply?
Nine times income is a lump-sum death and TPD guide. This product is a monthly benefit. They answer different absences.
Is it free?
Yes. The calculators and guides are free. A result appears in your browser before anyone asks for a phone number. Sending the form, if you want quotes for those figures, does not add a fee on this website.
Will you call me?
Not because you opened a page. We contact you only if you send the form or message us. You can read every result with the form left blank.
How does this site work?
The page does the arithmetic in your browser from the rules and the numbers you type. If you ask for quotes, we use your name, number and those figures only to reply about that enquiry. We do not sell the list. Personal data is handled under Singapore's Personal Data Protection Act. We are not an insurer and this is not financial advice.
Get a personalised breakdown
The calculator above runs in the browser with no phone number. Leave your details only if you want quotes or an audit for the same figures.
Sources
Facts on this page were checked against these sources on 30 October 2026.
- MoneySense: Understanding disability income insurance, updated 28 September 2026 moneysense.gov.sg, checked 30 October 2026
- MoneySense: Understanding health insurance moneysense.gov.sg, checked 30 October 2026
- MAS: Basic Financial Planning Guide mas.gov.sg, checked 30 October 2026
Fact-checked against HDB, IRAS, CPF, MAS.
