Key takeaways
- A cruise is not covered just because the ship leaves Singapore.
- Missed port, missed sailing and cabin confinement need their own lines.
- Medical care on board is still a medical limit, plus how you get ashore.
- We will not invent a cruise sub-limit the policy does not print.
The numbers
- Default if the schedule is silent
- Treat cruise-specific losses as limited or excluded
- Medical care
- Still the medical and evacuation limit
- Trip length
- Must fit the annual or single-trip cap
- Pre-existing conditions
- Still excluded unless a PreX plan names them
- Published market cap
- None we will invent
The short answer
Cruise travel insurance is not a third species beside annual and single-trip. It is a travel policy whose schedule mentions the things that happen on a ship: missing the sailing, a port that is cancelled, confinement to a cabin, and medical care that has to get you to a hospital on shore. If those lines are missing, do not fill them in with hope.
There is no single Singapore figure for “cruise cover up to S$X” that we can print as the market. Insurers set their own sub-limits. Quoting one brand’s campaign number as the rule would be an invention. Ask for the cruise section, or walk away.
The checks that still apply at sea
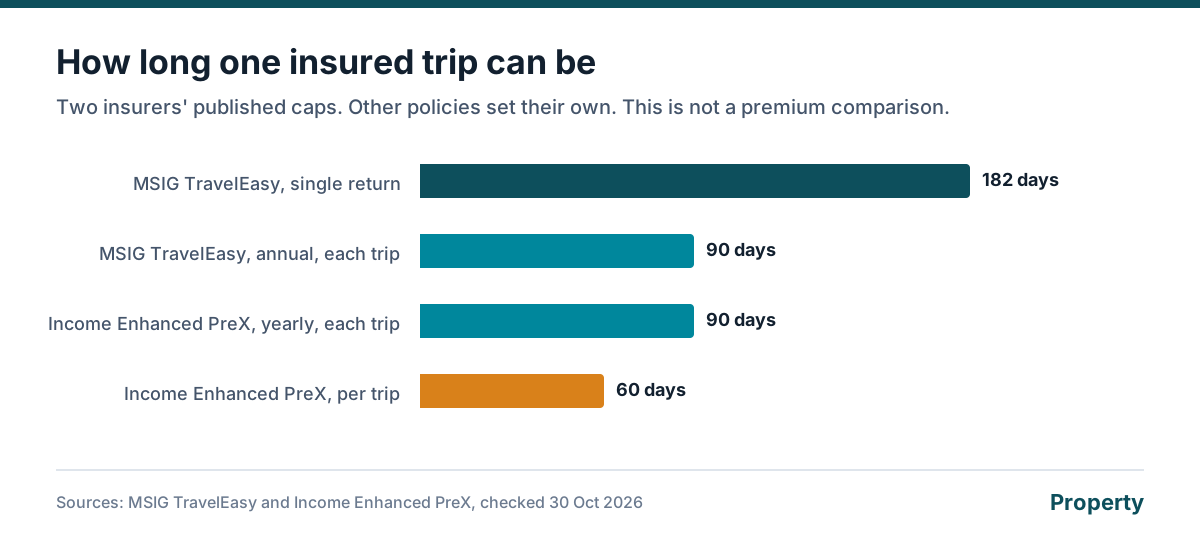
The trip has to fit the duration cap. A 100-day cruise fails a 90-day annual trip even if the cruise section is generous. MSIG’s annual cap is 90 days and its single return trip allows 182. Income’s Enhanced PreX per-trip plan allows 60 and the yearly plan 90. A condition you already have is still excluded on a standard plan. The sea does not waive that.
| Risk on a cruise | What to find in the wording |
|---|---|
| You miss the ship | A missed-departure or missed-connection section, and the hours of delay it demands |
| A port is skipped | Whether a missed port or itinerary change is paid, or excluded as a change by the operator |
| You are confined to the cabin | A cabin-confinement benefit, if any. It is not automatic hospital cash |
| You need a hospital ashore | Medical plus evacuation. The ship is not the end of the journey |
| An excursion | The activity list. Height, water and motors are where exclusions hide |
| The cruise is longer than the plan | The day cap. This one is not optional |
Buy the shape that fits the length
A short cruise in a year of other trips can sit on an annual plan if each trip, including the cruise, is inside the cap and the cruise section exists. A long repositioning voyage is a single-trip duration question first, on the single-trip page. Sports on the excursion are the adventure page. The hub is the index. We are not an insurer, and we will not invent a cruise payout.
Send me quotes for these figures
What you need before a quote
- Flat type, or condo and floor area
- What the contents would cost to replace
- What the renovation cost
- Age of the building, if you care about seepage tracing
- Whether you live there or rent it out
Other ways to compare in Singapore
- compareFIRST, the life-insurance shelf MoneySense points to. Direct Purchase plans there are commission-free up to the published cap.
- The insurer's own site, if you already know the product and want its illustration.
- A licensed insurance broker you choose. We do not name one and we do not publish a phone number for one.
- A bank that distributes the policy, if that is where you bank. Ask them what they are paid. We do not list a rate.
- The calculators on this site, which show a result before you send a form.
Questions on this topic
Does my annual plan cover a cruise automatically?
Only if the schedule says so. Annual versus single-trip is about how many journeys and how long. It does not add cruise benefits.
What if I miss the ship?
That is a missed-departure question. Some policies pay it. Some pay it only after a minimum delay, or not at all if you were already late. Read that section.
I am stuck in the cabin with an illness. Is that a hospital day?
Not unless the policy pays for cabin confinement. A hospital plan at home does not know you are at sea.
Are excursions covered?
Only when the activity is not excluded. The adventure-sports page is the neighbouring question. A tender to a beach can still be an excluded activity.
Is it free?
Yes. The calculators and guides are free. A result appears in your browser before anyone asks for a phone number. Sending the form, if you want quotes for those figures, does not add a fee on this website.
Will you call me?
Not because you opened a page. We contact you only if you send the form or message us. You can read every result with the form left blank.
How does this site work?
The page does the arithmetic in your browser from the rules and the numbers you type. If you ask for quotes, we use your name, number and those figures only to reply about that enquiry. We do not sell the list. Personal data is handled under Singapore's Personal Data Protection Act. We are not an insurer and this is not financial advice.
Get a personalised breakdown
The calculator above runs in the browser with no phone number. Leave your details only if you want quotes or an audit for the same figures.
Sources
Facts on this page were checked against these sources on 30 October 2026.
- MSIG: TravelEasy msig.com.sg, checked 30 October 2026
- MoneySense does not publish a cruise tariff. The schedule is the source. moneysense.gov.sg, checked 30 October 2026
Fact-checked against HDB, IRAS, CPF, MAS.