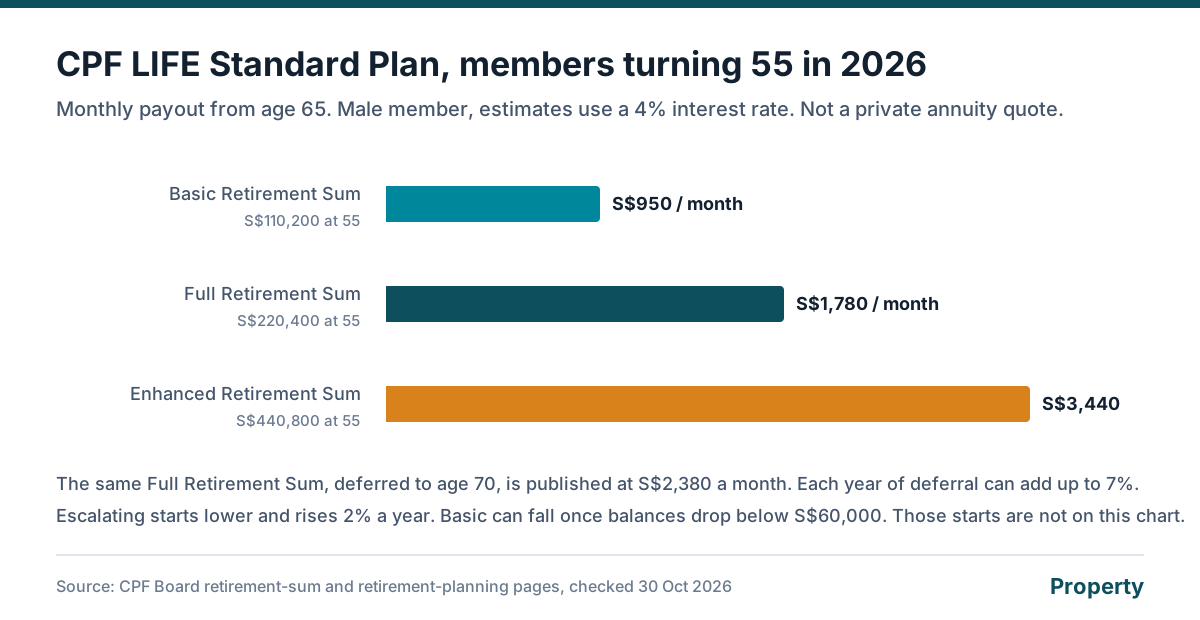
The S$950, S$1,780 and S$3,440 figures are CPF's Standard Plan estimates for a male member turning 55 in 2026 who sets aside the Basic, Full or Enhanced Retirement Sum, using a 4% interest rate, paid from 65. Deferring the Full Retirement Sum to 70 is published at S$2,380. Each year of deferral can add up to 7%, and the published step from 65 to 70 is not five years of 7% compounded. Escalating rises 2% a year from a lower start. Basic uses about 10% to 20% of Retirement Account savings as the annuity premium and can fall once balances drop below S$60,000. Payouts can be adjusted for interest rates and life expectancy.
How we calculate
Standard payouts are the published anchors, not a formula we invented. Income to a chosen age is the monthly figure times 12 times the years. Escalating compounds at 2% a year only after you confirm the figure is the Escalating start.
Inputs
- Retirement sum
- Plan
- Start age 65 or 70
- Monthly payout, which starts as the published Standard anchor
- A private monthly payout if you have one
Assumptions
- Anchors are male-member estimates at 4% interest for people turning 55 in 2026
- Payouts can be adjusted for interest and life expectancy
- A private annuity premium is not turned into a yield
Constants and where they come from
| Constant | Value used | Source |
|---|---|---|
| 2026 Standard anchors | S$950, S$1,780 and S$3,440 a month from 65. FRS from 70 is S$2,380 | cpf.gov.sg |
| Escalating step and deferral | 2% a year. Deferral up to 7% a year | cpf.gov.sg |
Key takeaways
- Payouts need at least S$60,000 when they start, for automatic inclusion.
- 2026 Standard estimates from 65: S$950, S$1,780, S$3,440.
- Those use a male member and 4% interest.
- The planner beats the cohort table for your own accounts.
The numbers
- Automatic inclusion
- Born 1958 or later, and at least S$60,000
- 2026 BRS estimate
- S$950 a month from 65, Standard
- 2026 FRS estimate
- S$1,780
- 2026 ERS estimate
- S$3,440
- Earliest start
- Age 65
The short answer
A CPF LIFE payout is a monthly amount for life, set from your savings, your plan and the age you start. There is no single “the CPF payout” for the country. There are published estimates for a cohort, and there is the figure on your planner.
For members turning 55 in 2026, Standard Plan, male member, 4% interest, from age 65: S$950 if the Basic Retirement Sum of S$110,200 was set aside, S$1,780 at the Full sum of S$220,400, and S$3,440 at the Enhanced sum of S$440,800. You join automatically if you were born in 1958 or later and you have at least S$60,000 when payouts start.
What moves the number
Four choices matter, and they are not the same dial.
The amount set aside at 55 is the retirement sum. The plan is Standard, Escalating or Basic. The start age is 65, or later up to 70. The estimate you see in a newspaper is usually Standard, male, from 65, at the Full sum. Change any one of those and the dollar changes. Escalating starts lower and then rises 2% a year. Basic can fall below the S$60,000 balance line. Deferral can add up to 7% a year, and the published Full-sum example of waiting until 70 is S$2,380, not a homemade multiple of S$1,780.
| Input | 2026 reference | If you change it |
|---|---|---|
| Savings at 55 | BRS, FRS or ERS | The payout scale moves with the savings |
| Plan | Standard, in the famous table | Escalating and Basic are different shapes |
| Start age | 65 | Up to 70. FRS example becomes S$2,380 |
| Who the table describes | Male member, 4% | Your planner is the personal figure |
The 2025 table is not a typo
Ask CPF’s payout table for the previous cohort is lower because the sums were lower: about S$930 from a S$106,500 Basic sum and S$1,730 from a S$213,000 Full sum, again Standard, male. If you turn 55 in 2025, that is your reference, not S$1,780. The Full sum page and the Basic sum page keep the cohorts apart.
The calculator on this page starts from the 2026 Full-sum anchor so you see a real published figure before you type anything else. Replace it with the planner number when you have it. A private annuity quote is optional and is not invented. The hub is the comparison. The Standard page is the level plan in more detail. We are not CPF.
What you need before a quote
- Which retirement sum you set aside, or the figure on your CPF planner
- Standard, Escalating or Basic
- Whether payouts start at 65 or 70
- A private annuity's monthly payout, if you have a quote
Other ways to compare in Singapore
- compareFIRST, the life-insurance shelf MoneySense points to. Direct Purchase plans there are commission-free up to the published cap.
- The insurer's own site, if you already know the product and want its illustration.
- A licensed insurance broker you choose. We do not name one and we do not publish a phone number for one.
- A bank that distributes the policy, if that is where you bank. Ask them what they are paid. We do not list a rate.
- The calculators on this site, which show a result before you send a form.
Questions on this topic
Why is my planner different from S$1,780?
Because S$1,780 is the Full Retirement Sum, Standard Plan, male member, 4%, for people turning 55 in 2026 who start at 65. A different balance, sex, plan or start age is a different payout.
Do payouts last past 90?
Yes. CPF LIFE is for life, including past 90. A private term annuity may stop. That is the point of the national scheme.
What if I have under S$60,000?
Automatic CPF LIFE inclusion uses that threshold. Below it, CPF describes Retirement Account payouts that last until the savings run out, not the lifelong pool.
Can the payout change after it starts?
CPF says estimates can be adjusted for long-term interest rates or life expectancy. Escalating also rises 2% a year by design. Basic can fall when balances are low.
Is it free?
Yes. The calculators and guides are free. A result appears in your browser before anyone asks for a phone number. Sending the form, if you want quotes for those figures, does not add a fee on this website.
Will you call me?
Not because you opened a page. We contact you only if you send the form or message us. You can read every result with the form left blank.
How does this site work?
The page does the arithmetic in your browser from the rules and the numbers you type. If you ask for quotes, we use your name, number and those figures only to reply about that enquiry. We do not sell the list. Personal data is handled under Singapore's Personal Data Protection Act. We are not an insurer and this is not financial advice.
Get a personalised breakdown
The calculator above runs in the browser with no phone number. Leave your details only if you want quotes or an audit for the same figures.
Sources
Facts on this page were checked against these sources on 30 October 2026.
- CPF Board: What is the CPF retirement sum? cpf.gov.sg, checked 30 October 2026
- CPF Board: Your complete guide to retirement planning cpf.gov.sg, checked 30 October 2026
- CPF Board: CPF LIFE cpf.gov.sg, checked 30 October 2026
- Ask CPF: payout reference for the 2025 age-55 cohort ask.gov.sg, checked 30 October 2026
Fact-checked against HDB, IRAS, CPF, MAS.

