Key takeaways
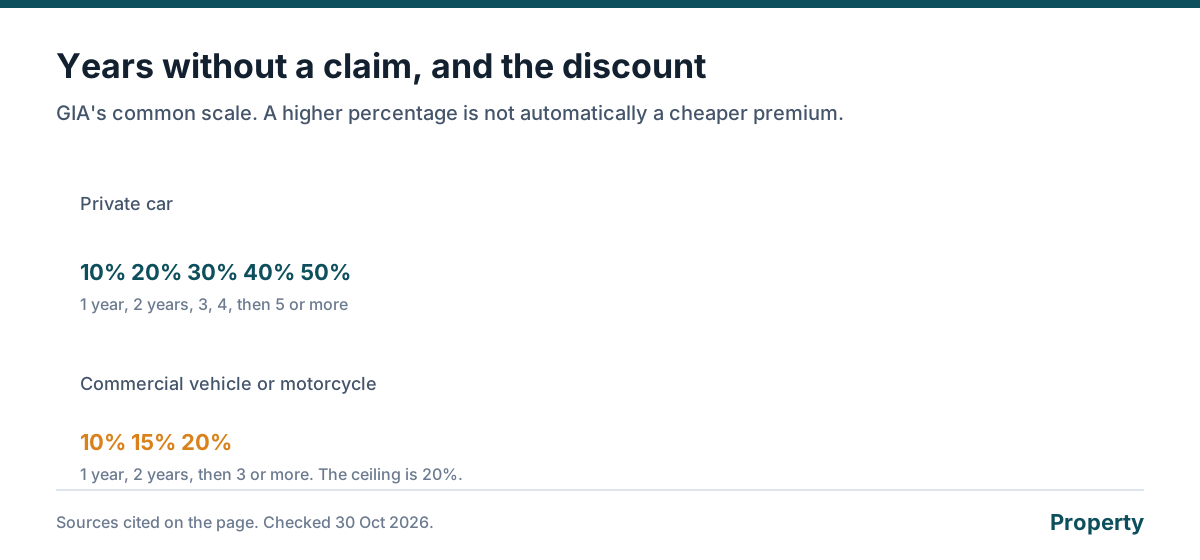
- Private car: 10, 20, 30, 40, then 50 percent.
- Commercial vehicle or motorcycle: 10, 15, then 20 percent.
- The discount is one factor in the premium, not the whole price.
- It can move to another car you own, not to two cars at once.
The numbers
- 1 claim-free year, car
- 10%
- 5 or more, car
- 50%
- 3 or more, motorcycle or commercial
- 20%
- Belongs to
- You, for that vehicle
- Not a
- Protector, and not a premium guarantee
The short answer
A no-claim discount is the insurer’s reduction on the renewal premium after you go a year or more without a claim. GIA’s common private-car steps are 10% after one year, 20% after two, 30% after three, 40% after four, and 50% after five or longer. Commercial vehicles and motorcycles are 10%, 15%, and 20% from the third year.
That percentage is not the price of the policy. GIA’s own warning is that a quote built on a higher discount can still cost more than another insurer’s quote built on a lower one. Shop the dollars. Do not shop the badge.
What the discount follows
It follows you, not the number plate, with limits. Change cars and the record can come with you. It does not duplicate onto a second car. A spouse can be given the discount only at the current insurer, which is a different question from switching brands. A stretch with no car at all is usually kept for up to 24 months, sometimes 12, and that clock is the insurer’s.
The percentage also is not a promise that next year’s rate card stays still. Insurers reprice. A 50% discount on a higher base can cost more than a 40% discount did last year. Hold the base flat only when you are doing arithmetic, and say that you held it flat.
| Years without a claim | Private car | Commercial or motorcycle |
|---|---|---|
| 1 | 10% | 10% |
| 2 | 20% | 15% |
| 3 | 30% | 20% |
| 4 | 40% | 20% |
| 5 or more | 50% | 20% |
Where a claim fits
One private-car claim does not always delete the record. From 50% the common cut is to 20%. From 40% it is to 10%. From 30% or less it is to zero. Two claims in the year go to zero. A commercial vehicle or motorcycle goes to zero on one claim. If you were wholly not at fault in a crash with another vehicle, GIA says the discount may not move. The loss page is that table on its own. The 50% page is what the ceiling is worth in percentage points. The protector, if you buy one, is a different contract, explained on what the add-on is. The hub collects them. We are not an insurer.
Send me quotes for these figures
What you need before a quote
- Flat type, or condo and floor area
- What the contents would cost to replace
- What the renovation cost
- Age of the building, if you care about seepage tracing
- Whether you live there or rent it out
Other ways to compare in Singapore
- compareFIRST, the life-insurance shelf MoneySense points to. Direct Purchase plans there are commission-free up to the published cap.
- The insurer's own site, if you already know the product and want its illustration.
- A licensed insurance broker you choose. We do not name one and we do not publish a phone number for one.
- A bank that distributes the policy, if that is where you bank. Ask them what they are paid. We do not list a rate.
- The calculators on this site, which show a result before you send a form.
Questions on this topic
Does 50% at insurer A beat 40% at insurer B?
Not necessarily. GIA says a quote that starts from a higher discount can still be more expensive than a rival's quote from a lower one. Compare the dollars.
Is the discount on the car or on me?
On you, for that vehicle. Sell the car and buy another, and you generally keep it. Own two, and each one earns its own.
Do I get it in the first year?
The first renewal after a claim-free year is 10% on the common scale. A brand-new policy has not earned a year yet.
What is the difference between this and a protector?
The discount is the percentage you earned. The protector is an optional extra that, in GIA's 50% private-car example, softens one claim if you stay with the insurer.
Is it free?
Yes. The calculators and guides are free. A result appears in your browser before anyone asks for a phone number. Sending the form, if you want quotes for those figures, does not add a fee on this website.
Will you call me?
Not because you opened a page. We contact you only if you send the form or message us. You can read every result with the form left blank.
How does this site work?
The page does the arithmetic in your browser from the rules and the numbers you type. If you ask for quotes, we use your name, number and those figures only to reply about that enquiry. We do not sell the list. Personal data is handled under Singapore's Personal Data Protection Act. We are not an insurer and this is not financial advice.
Get a personalised breakdown
The calculator above runs in the browser with no phone number. Leave your details only if you want quotes or an audit for the same figures.
Sources
Facts on this page were checked against these sources on 30 October 2026.
- GIA: No Claims Discount gia.org.sg, checked 30 October 2026
Fact-checked against HDB, IRAS, CPF, MAS.
