A Schengen short-stay visa needs travel medical insurance of at least EUR 30,000 for the whole stay, valid in the Member States, covering repatriation, urgent medical care, emergency hospital treatment and death. That is Article 15 of Regulation (EC) No 810/2009. We do not convert it to Singapore dollars. Income's Enhanced PreX plan is an example that names a pre-existing sub-limit. MSIG states that TravelEasy excludes pre-existing conditions and that its Pre-Ex cover is single-trip. Cruise, adventure sports and epidemic sections are policy wording, not a feature of annual versus single-trip.
How we calculate
Break-even trips equal the annual premium divided by one single-trip premium. The saving is the single-trip stack minus the annual premium. A longest trip above the cap you typed is flagged. No premium is looked up.
Inputs
- Single-trip premium
- Annual premium
- Trips you expect
- Longest trip and the annual cap
- Pre-existing and Schengen toggles
Assumptions
- The two quotes match on people and medical limit
- Day caps shown in the hint are two insurers' published rules, not a market rule
- Schengen's minimum is EUR 30,000 and is not converted to Singapore dollars
Constants and where they come from
| Constant | Value used | Source |
|---|---|---|
| Schengen minimum | EUR 30,000 including repatriation | eur-lex.europa.eu |
| Example day caps | MSIG annual 90 days, single 182. Income Enhanced PreX 60 or 90 | msig.com.sg |
On this page
Key takeaways
- Break-even equals annual premium divided by single-trip premium.
- A slogan that says two trips is one insurer's framing.
- A trip longer than the annual cap needs a single-trip policy.
- The medical limit and the exclusions have to match, or the division is fake.
The numbers
- Formula
- Annual premium ÷ one single-trip premium
- Then
- Count only trips that fit the cap and the exclusions
- MSIG annual cap
- 90 days
- MSIG single cap
- 182 days
- Allianz's own framing
- Single for one or two trips. Not a rule
The short answer
Annual versus single-trip is a division, then a calendar check. Take the annual premium. Divide by the premium of one comparable single trip. The result is how many of those trips you must take before the year plan costs less. If you will take more than that, and every trip fits the annual plan’s day cap, and the exclusions match, the year plan wins on price. If any of those three fails, the division is not the decision.
Allianz says its own single-trip plan is for people likely to make one or two trips, and its annual plan caps each trip at 90 days. That is a product description. It is not your break-even.
The calculator will not run until both premiums are typed. There is no hidden price list.
The cap that overrides a cheap year
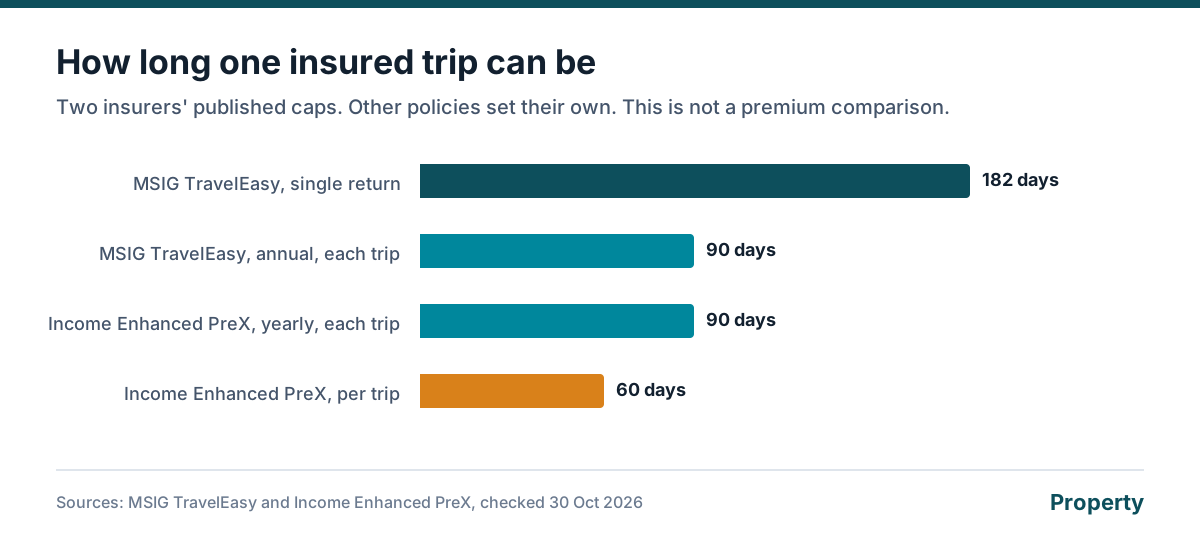
MSIG TravelEasy: annual trips stop at 90 days, a single return trip can last 182. Income Enhanced PreX: 90 days on the yearly plan, 60 on the per-trip plan. A stay of 100 days fails the MSIG annual cap and fails Income’s per-trip cap. It can fit MSIG’s single-trip cap. The premium comparison is irrelevant until the stay fits.
| Step | What you use |
|---|---|
| 1 | Two quotes with the same medical limit and the same people |
| 2 | Annual ÷ single = break-even trip count |
| 3 | Your real trip count, not a hopeful one |
| 4 | Longest stay versus the annual cap |
| 5 | Exclusions: condition, cruise, sport, epidemic section |
Flags that are not in the premium
A pre-existing condition, a Schengen visa, and a cruise are not solved by taking more trips. The condition page, the Schengen page and the cruise page are those flags. The calculator has toggles so the result can say the price is not the whole answer. The hub is the cluster. We are not an insurer.
What you need before a quote
- A single-trip premium and an annual premium for the same people and medical limit
- How many trips you will take, and the longest one in days
- The annual plan's cap on one trip
- Whether a pre-existing condition or a Schengen visa is in play
Other ways to compare in Singapore
- compareFIRST, the life-insurance shelf MoneySense points to. Direct Purchase plans there are commission-free up to the published cap.
- The insurer's own site, if you already know the product and want its illustration.
- A licensed insurance broker you choose. We do not name one and we do not publish a phone number for one.
- A bank that distributes the policy, if that is where you bank. Ask them what they are paid. We do not list a rate.
- The calculators on this site, which show a result before you send a form.
Questions on this topic
Is the answer always two or three trips?
No. If the single trip is expensive because it is long, or cheap because it is short, the quotient moves. Type the quotes.
What if the annual plan excludes my condition?
Then it is not the same cover. The division does not apply. Price a plan that names the condition.
Do family premiums change the formula?
Use the family annual premium and the family single-trip premium, not a mix of one adult and a family. The calculator has a label for that.
Can I ignore the day cap if I am under the break-even?
No. A 100-day trip on a 90-day plan is uncovered for the extra days, however clever the premium looks.
Is it free?
Yes. The calculators and guides are free. A result appears in your browser before anyone asks for a phone number. Sending the form, if you want quotes for those figures, does not add a fee on this website.
Will you call me?
Not because you opened a page. We contact you only if you send the form or message us. You can read every result with the form left blank.
How does this site work?
The page does the arithmetic in your browser from the rules and the numbers you type. If you ask for quotes, we use your name, number and those figures only to reply about that enquiry. We do not sell the list. Personal data is handled under Singapore's Personal Data Protection Act. We are not an insurer and this is not financial advice.
Get a personalised breakdown
The calculator above runs in the browser with no phone number. Leave your details only if you want quotes or an audit for the same figures.
Sources
Facts on this page were checked against these sources on 30 October 2026.
- MSIG: TravelEasy msig.com.sg, checked 30 October 2026
- Income: Enhanced PreX Travel Insurance income.com.sg, checked 30 October 2026
- Allianz Assistance Singapore: Schengen and annual framing allianz-assistance.com.sg, checked 30 October 2026
Fact-checked against HDB, IRAS, CPF, MAS.
