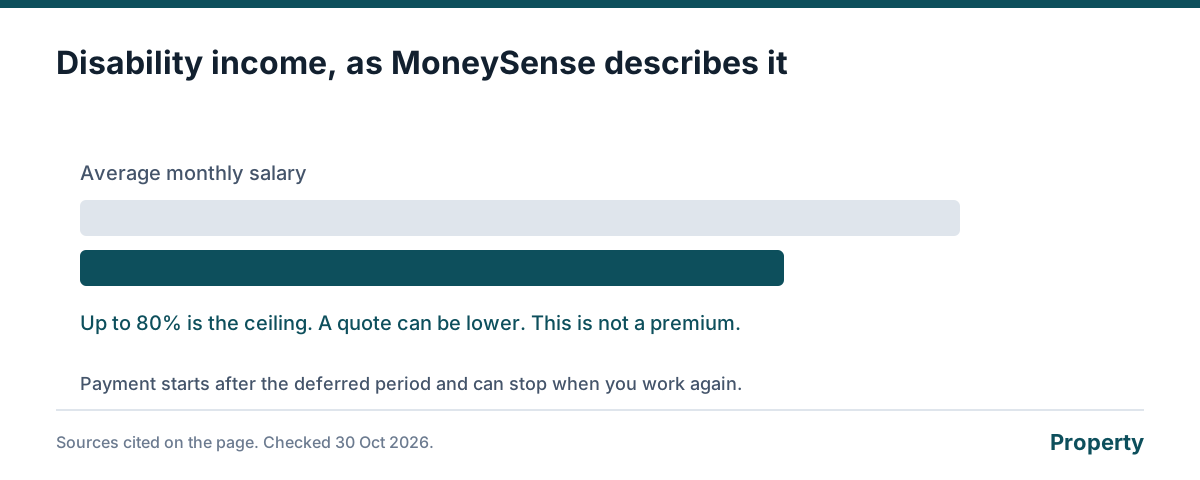
MoneySense, updated 28 September 2026: disability income pays a fixed monthly amount if you cannot work because of illness or accident, up to 80% of average monthly salary, after a deferred period, and it stops or reduces when you can work again. The definition of disability is the insurer's. A personal accident plan is a different contract: it follows an accident schedule and does not replace income lost to illness. Total and permanent disability on a life policy is a lump sum under that policy's definition, not this monthly benefit. We do not price either product.
How we calculate
Months of salary equal the lump sum divided by salary. The 80% line is 0.8 times salary. A monthly benefit above that line is flagged. The full-term figure is the monthly benefit times 12 times the years you typed.
Inputs
- Monthly salary
- Personal accident lump sum
- Disability income per month
- Deferred period and benefit years
Assumptions
- 80% is MoneySense's ceiling, not the benefit you will be offered
- The lump sum is accident-only
- Recovery can stop the monthly benefit before the term you typed
Constants and where they come from
| Constant | Value used | Source |
|---|---|---|
| 80% ceiling | Up to 80% of average monthly salary | moneysense.gov.sg |
Key takeaways
- It pays for an accident, on a schedule.
- A stroke, cancer or a bad back from years at a desk is not this benefit.
- Months of salary = lump sum ÷ monthly pay.
- It is not disability income, and it is not TPD on a life policy.
The numbers
- Pays for
- Accidental death and scheduled injuries
- Does not pay for
- Illness
- Useful test
- Lump sum divided by monthly salary
- Disability income
- A different product, monthly, up to 80% of salary
- Travel accident section
- Not the same as a year-round PA policy
The short answer
Personal accident insurance in Singapore pays when an accident causes death or an injury on the policy’s schedule. It is not a mini life policy, and it is not income protection. Illness sits outside it. A stroke, cancer, or a back that failed after years at a desk is the wrong story for this contract.
The calculator turns a lump sum you type into months of the salary you type. That is the only honest way to read a large number next to a small premium. We do not have a public tariff of PA prices worth printing as the market.
What the schedule is doing
Insurers print a table: accidental death at one end, and lesser injuries at a fraction of the sum assured. Losing a thumb is not the same claim as dying. Because those fractions differ by policy, this page will not pretend there is a national thumb percentage. Ask for the schedule before you compare two premiums.
A travel policy’s personal accident section is a cousin, not a substitute. It ends when the trip ends, and an excluded sport can remove it. The adventure page is that hole. A Tuesday commute is this policy’s job, if an accident is the risk you are buying.
| Product | The event | The payment |
|---|---|---|
| Personal accident | An accident, on the schedule | A lump sum or a fraction of it |
| Disability income | Illness or injury that stops work | A monthly amount, up to 80% of average salary |
| Hospital cash | A day in a ward | A fixed sum per day, which may not match the bill |
| Term life TPD | The life policy’s disability definition | A lump sum, often a strict test |
| Travel PA section | An accident on that trip | A sum that ends with the trip |
Months, not marketing
Type the salary and the accidental-death figure. If the result is four months of pay, the policy is four months of pay, however round the million looks. Disability income is the contract that tries to replace a salary for years, and it is capped in MoneySense’s description at 80% of average monthly salary. That is the disability income page. The difference from a life policy is the life comparison. The hub holds both calculators’ ideas together. We are not an insurer.
What you need before a quote
- Average monthly salary
- The personal accident lump sum on the schedule
- The disability income benefit per month, the wait, and how many years it can run
Other ways to compare in Singapore
- compareFIRST, the life-insurance shelf MoneySense points to. Direct Purchase plans there are commission-free up to the published cap.
- The insurer's own site, if you already know the product and want its illustration.
- A licensed insurance broker you choose. We do not name one and we do not publish a phone number for one.
- A bank that distributes the policy, if that is where you bank. Ask them what they are paid. We do not list a rate.
- The calculators on this site, which show a result before you send a form.
Questions on this topic
Does it pay 100% for a broken arm?
Not as a rule. Schedules pay a percentage of the sum assured for listed injuries, and the full sum for accidental death. We will not print a generic percentage. Your schedule is the list.
I work at a desk and my back failed. Is that an accident?
A sudden external accident might be. Wear and tear is the exclusion this product is built around. If the loss is income from illness, you wanted disability income.
Is a large sum a good deal if the premium is small?
Only if the accidents you are imagining are on the schedule, and the months of salary are enough. A small premium can mean a narrow schedule.
Does my travel policy's personal accident section replace this?
No. It lasts for the trip. This policy is the one that is meant to be in force on an ordinary Tuesday.
Is it free?
Yes. The calculators and guides are free. A result appears in your browser before anyone asks for a phone number. Sending the form, if you want quotes for those figures, does not add a fee on this website.
Will you call me?
Not because you opened a page. We contact you only if you send the form or message us. You can read every result with the form left blank.
How does this site work?
The page does the arithmetic in your browser from the rules and the numbers you type. If you ask for quotes, we use your name, number and those figures only to reply about that enquiry. We do not sell the list. Personal data is handled under Singapore's Personal Data Protection Act. We are not an insurer and this is not financial advice.
Get a personalised breakdown
The calculator above runs in the browser with no phone number. Leave your details only if you want quotes or an audit for the same figures.
Sources
Facts on this page were checked against these sources on 30 October 2026.
- MoneySense: Understanding disability income insurance, updated 28 September 2026 moneysense.gov.sg, checked 30 October 2026
- MoneySense: Understanding health insurance moneysense.gov.sg, checked 30 October 2026
- MoneySense: Assessing your insurance needs moneysense.gov.sg, checked 30 October 2026
Fact-checked against HDB, IRAS, CPF, MAS.
