On this page
Key takeaways
- Premiums buy units in a fund.
- Units are sold to pay for the insurance and the charges.
- You bear the investment risk on what is left.
- An ILP is a poor substitute for term if all you wanted was cover.
The numbers
- Premium buys
- Units in the sub-funds you pick
- Then
- Some units are sold for cover and fees
- Risk
- Yours, on the remaining units
- Compared with term
- A bundle, and usually costlier for pure cover
- Cash value
- The value of the units, which can fall
The short answer
An investment-linked policy in Singapore is two things in one contract. Your premium buys units in the funds you chose. Some of those units are then sold to pay for the life insurance and the policy charges. The units that remain are the investment. If the funds fall, or if charges consume units faster than you expected, the value falls. MoneySense is plain about who carries that risk: you do.
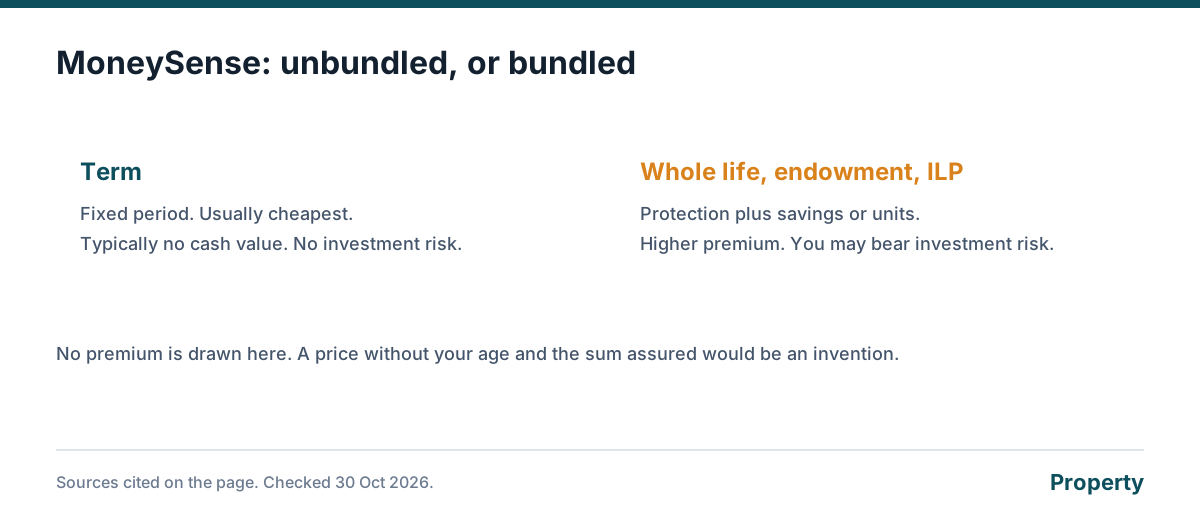
It is not a fixed deposit, and it is not term insurance with a loyalty bonus. It is a bundled product, in the same MoneySense column as whole life and endowment, and bundled products generally cost more than term if the job was only protection.
Follow a premium through the policy
Start with S$1 of premium in your head, not as a market quote. Part of that dollar buys units. Later, units are cancelled to pay for the sum assured and for fees. What is left fluctuates. Two ILPs with the same premium can leave very different amounts invested if one has heavier insurance charges or a larger sum assured. The headline premium hides that split. The policy’s charge page is the split.
| Question | Where the answer is |
|---|---|
| How much of the premium stays invested? | The benefit illustration’s allocation and charge table, not the sales slide |
| Can the units fall? | Yes. You bear the fund risk |
| Is there a guaranteed cash value like non-participating whole life? | Usually no. The value is the units |
| Is this cheaper than buying term and a fund separately? | Only a quote-by-quote comparison can say. Do not assume the bundle is efficient |
| What if I stop paying? | Units may be sold until they run out, and the cover can lapse |
When an ILP is the wrong aisle
If you want a large death benefit until your children finish school, price a term plan first. The ILP versus term page is that aisle. If you want savings toward a date, with a guaranteed slice, look at an endowment and read its guaranteed column, on the endowment page. If you will genuinely invest the difference yourself, the buy term page is the behaviour. The calculator on the term and whole life hub will compound a premium gap you type. It will not model unit cancellation inside a named ILP, because those charges are policy-specific and we will not invent a fee. We are not an adviser.
Guides on this ILP hub
Each question below has its own page. Surrender steps, the surrender calculator, the fee glossary, ILP versus a unit trust or ETF, and the named-plan reviews sit on their own URLs and are linked from the pages that need them, rather than repeated here.
| Question | Page |
|---|---|
| Is an ILP worth it? | Decision guide |
| ILP or whole life? | Comparison |
| How do I read the illustration? | 0%, B% and C% |
| What is a 101 ILP? | Death benefit shapes |
| Single premium or regular premium? | The two categories |
| Can I withdraw some units? | Partial withdrawal |
| What if I stop paying? | Premium holiday |
| Can I cut the sum assured? | Reduce the cover |
| Can I pay more in? | Top-ups |
| How do I change funds? | Fund switching |
| How do I read a sub-fund? | Prices and factsheets |
| What is a welcome bonus? | Bonus units |
| ILP or CPF LIFE? | Different jobs |
| Can CPF or SRS pay the premium? | The gates |
| Is the unit value SDIC-protected? | PPF Scheme |
| ILP or a robo-adviser? | Wrapper versus portfolio |
| What do buyers get wrong? | Twelve mistakes |
Fees, surrender by insurer, and the value calculator are the next doors if you already hold a policy: fees, surrender, calculator, ILP versus a fund you buy yourself, and the review checklist. The form on every page in this table is a free ILP policy review. The WhatsApp button asks for the same thing.
Listicles
Numbered checks for this cover. They do not rank insurers.
| Page | What it is |
|---|---|
| 10 Questions to Ask Before You Buy an ILP | A list, not a premium table |
| 10 Things to Check on an ILP Statement | A list, not a premium table |
Send me quotes for these figures
What you need before a quote
- The product summary charge table and the latest statement
- Account value, the unit price date, and any surrender charge
- Whether you still need the death benefit, a critical illness rider, or other cover
- A replacement term quote, if you would buy cover again
- Fund factsheets for the sub-funds you actually hold
Other ways to compare in Singapore
- compareFIRST, the life-insurance shelf MoneySense points to. Direct Purchase plans there are commission-free up to the published cap.
- The insurer's own site, if you already know the product and want its illustration.
- A licensed insurance broker you choose. We do not name one and we do not publish a phone number for one.
- A bank that distributes the policy, if that is where you bank. Ask them what they are paid. We do not list a rate.
- The calculators on this site, which show a result before you send a form.
Questions on this topic
Is the illustrated return a promise?
No. Unit prices move. An illustration is a scenario. MoneySense says you bear the investment risk.
Why did my units fall even when markets rose?
Because units are cancelled to pay for insurance and fees. A rising fund can still shrink your holding if charges take more units than the price gain replaces. Read the charge table.
Can I pick the funds later?
Many ILPs allow switches. Switches can have charges and are still your risk. The policy wording is the list of what is allowed.
Should I buy an ILP for a child?
Only if you want the investment and the charges, not because it sounds like education savings. An endowment is a different savings contract. Term on the parent insures the income.
Is it free?
Yes. The calculators and guides are free. A result appears in your browser before anyone asks for a phone number. Sending the form, if you want quotes for those figures, does not add a fee on this website.
Will you call me?
Not because you opened a page. We contact you only if you send the form or message us. You can read every result with the form left blank.
How does this site work?
The page does the arithmetic in your browser from the rules and the numbers you type. If you ask for quotes, we use your name, number and those figures only to reply about that enquiry. We do not sell the list. Personal data is handled under Singapore's Personal Data Protection Act. We are not an insurer and this is not financial advice.
Get a personalised breakdown
The calculator above runs in the browser with no phone number. Leave your details only if you want quotes or an audit for the same figures.
Sources
Facts on this page were checked against these sources on 8 November 2026.
- MoneySense: Comparing term and bundled life insurance moneysense.gov.sg, checked 8 November 2026
- MoneySense: Insurance basics and compareFIRST moneysense.gov.sg, checked 8 November 2026
Fact-checked against HDB, IRAS, CPF, MAS.
