Key takeaways
- One claim, same insurer, at 50% with a protector: stays at 50%.
- One claim, new insurer: 20%, protector or not.
- Two claims, new insurer: 0%.
- GIA says protected NCD may not transfer, and a protector does not force renewal.
The numbers
- One claim, stay
- 50%
- One claim, switch
- 20%
- Two claims, stay
- 20%
- Two claims, switch
- 0%
- Three or more
- 0% either way
The short answer
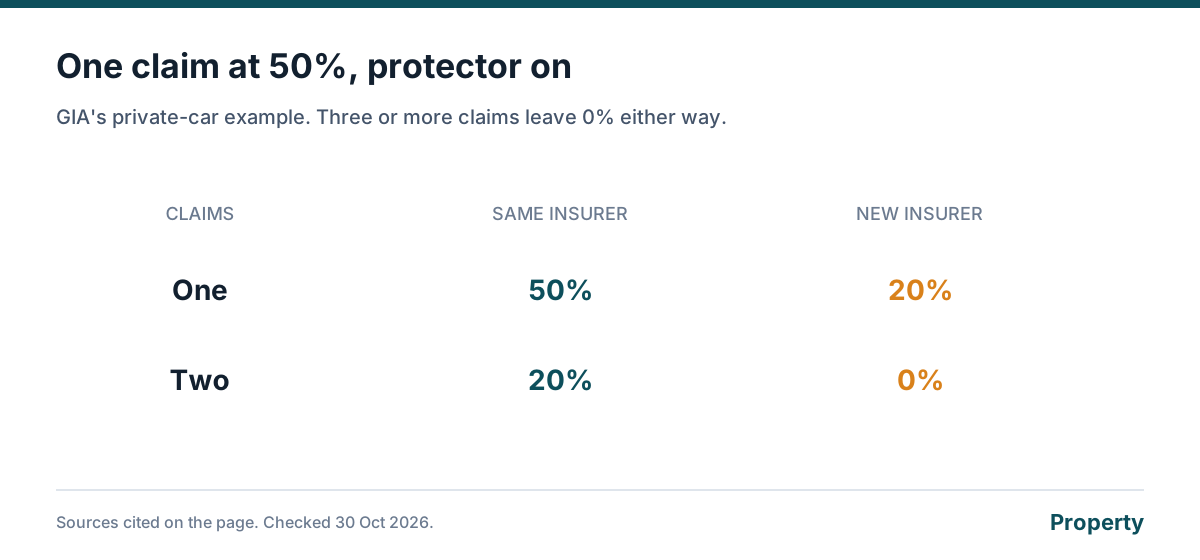
Switching insurer after a claim is the case where an NCD protector does the least. GIA’s published private-car example, for someone already at 50%, is blunt. One claim renewed with the same insurer keeps 50%. The same claim renewed with a new insurer is 20%. That 20% is exactly where you land with no protector at all.
Two claims leave 20% if you stay and nothing if you leave. Three or more leave nothing in both columns. GIA adds that protected NCD may not transfer, and that having a protector does not stop the insurer cancelling or refusing renewal.
The table people skip
Read down the new-insurer column before you pay for the add-on. If your habit is to remarket every renewal, a single at-fault claim makes the protector’s headline benefit disappear. The product still costs money. The break-even page is where you put your own premium next to that fact. This page is only the switch.
| Claims this year, starting from 50% | Same insurer | New insurer |
|---|---|---|
| None | 50%, and a plain discount can move | 50% if they accept your proof. The premium can still differ |
| One | 50% with a protector, 20% without | 20% either way, on the published example |
| Two | 20% with a protector, 0% without | 0% |
| Three or more | 0% | 0% |
A clean record is a different move
Do not confuse this with a claim-free switch. GIA says an ordinary NCD can transfer when you change insurer, and can transfer to another car you own. It cannot cover two cars at once, and a spouse only receives it at the current insurer. Those rules are on the spouse page and the discount page.
What you should carry to the new insurer is written proof of the percentage and of whether a claim was recorded. A protected claim that you describe as “still 50%” will be wrong if the new insurer applies the 20% cell. Ask them which cell they are using, in writing, before you cancel the old policy. If the old insurer has already refused renewal, you are a new-insurer case whether you wanted to be or not.
The ordinary, unprotected cut is explained on when you lose NCD. The hub is the cluster index. We are not an insurer, and we do not know your renewal offer.
Send me quotes for these figures
What you need before a quote
- Flat type, or condo and floor area
- What the contents would cost to replace
- What the renovation cost
- Age of the building, if you care about seepage tracing
- Whether you live there or rent it out
Other ways to compare in Singapore
- compareFIRST, the life-insurance shelf MoneySense points to. Direct Purchase plans there are commission-free up to the published cap.
- The insurer's own site, if you already know the product and want its illustration.
- A licensed insurance broker you choose. We do not name one and we do not publish a phone number for one.
- A bank that distributes the policy, if that is where you bank. Ask them what they are paid. We do not list a rate.
- The calculators on this site, which show a result before you send a form.
Questions on this topic
So the protector is useless if I shop around every year?
For a single claim, on the published 50% example, yes. The new insurer's figure matches the unprotected cut. You would be paying an add-on that does not change that outcome.
I have not claimed. Can I move a plain 50%?
An ordinary discount can move with you to a new insurer. The warning is about the protected percentage after a claim, and about whether the new insurer accepts the proof.
Does the new insurer have to match my old 50%?
No. GIA also says a higher discount does not guarantee a lower premium. Get the dollar quote.
What if the old insurer will not renew me?
The protector does not stop that. If you are forced to leave after a claim, price the policy at 20%, not at a protected 50%.
Is it free?
Yes. The calculators and guides are free. A result appears in your browser before anyone asks for a phone number. Sending the form, if you want quotes for those figures, does not add a fee on this website.
Will you call me?
Not because you opened a page. We contact you only if you send the form or message us. You can read every result with the form left blank.
How does this site work?
The page does the arithmetic in your browser from the rules and the numbers you type. If you ask for quotes, we use your name, number and those figures only to reply about that enquiry. We do not sell the list. Personal data is handled under Singapore's Personal Data Protection Act. We are not an insurer and this is not financial advice.
Get a personalised breakdown
The calculator above runs in the browser with no phone number. Leave your details only if you want quotes or an audit for the same figures.
Sources
Facts on this page were checked against these sources on 30 October 2026.
- GIA: No Claims Discount gia.org.sg, checked 30 October 2026
Fact-checked against HDB, IRAS, CPF, MAS.
