Key takeaways
- Wholly not at fault, with another vehicle, may leave the discount alone.
- Other single claims on a private car: 50% becomes 20%, 40% becomes 10%.
- Tell the insurer within 24 hours or the next working day.
- A police report does not replace the report to the insurer.
The numbers
- Not-at-fault crash with another vehicle
- Discount may be unchanged
- One claim from 50%
- 20% at renewal
- Two claims in the year
- 0%
- Tell the insurer
- 24 hours or the next working day
- Police report
- Does not replace the insurer report
The short answer
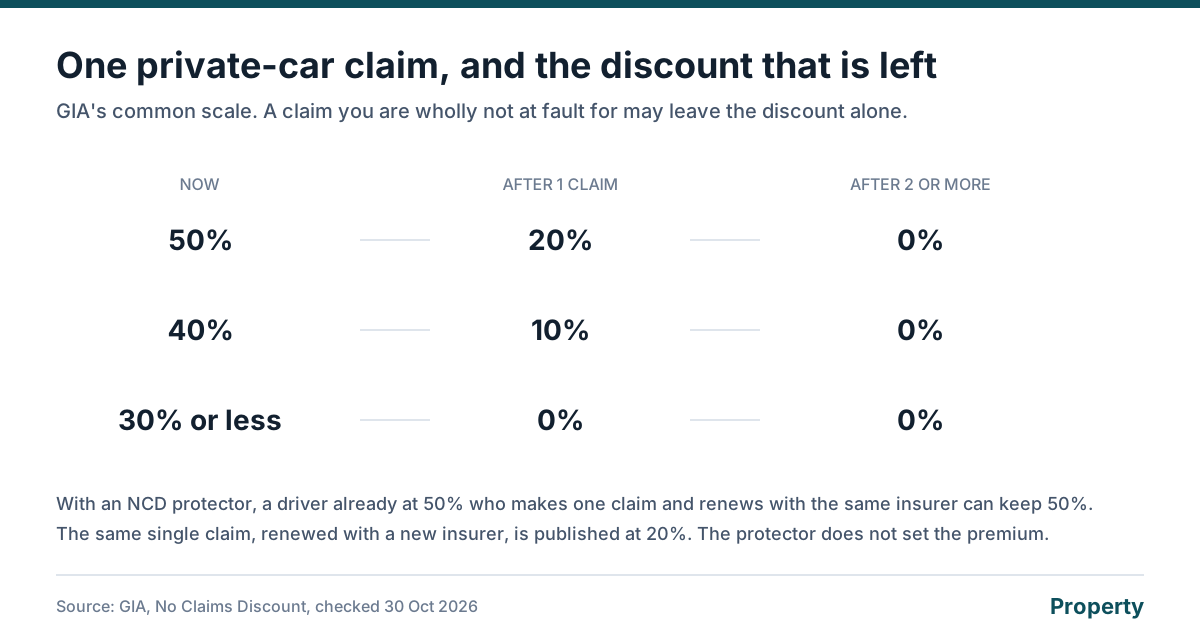
The no-claim discount after an accident is a renewal question, and it is not automatic. GIA says you do not necessarily lose it. If you are found totally not at fault in an accident that involved another vehicle, the discount may stay. In other cases it may be cut. One private-car claim, when it does count, takes 50% to 20%, 40% to 10%, and 30% or less to zero. A second claim in the same year takes whatever is left to zero.
You report the accident anyway. The discount rule and the reporting rule are not substitutes.
The phone call is not the discount
GIA’s motor claims steps are practical. Exchange particulars. Photograph the scene and the damage. Call the insurer’s hotline if you need a tow or advice. Report within 24 hours or by the next working day. If someone is hurt, or the case is one of the traffic-police categories (death, government property, a foreign vehicle, a pedestrian or cyclist, a hit-and-run, or the injury tests in the guide), make that report too. Filing with the police does not file with the insurer. Skip the insurer and the guide lists three consequences: the claim can be refused, the discount can be docked at renewal, and renewal itself can be refused.
Paying a small repair out of pocket, and hoping the record stays clean, is how people miss that window. Ask the insurer before you decide the claim is too small to mention.
| Situation | Discount at the next renewal, on GIA’s common private-car method |
|---|---|
| Wholly not at fault, another vehicle involved | May be unchanged. Confirm with the insurer |
| One claim, you were at 50% | 20% |
| One claim, you were at 40% | 10% |
| One claim, you were at 30% or less | 0% |
| Two or more claims in the year | 0% |
| Commercial vehicle or motorcycle, one claim | 0% |
Protector, market value, and the loan
A protector, if the schedule has one, is about the renewal percentage. On the published 50% private-car example it keeps 50% when you stay with the insurer. It does not choose the repair shop, and it does not fill a gap between the payout and the hire-purchase balance. That gap is the PARF and loan calculator. The ordinary cut, with no protector, is the loss page. The hub is the index. We are not an insurer, and fault is a finding, not a guess you should print on the claim form.
Send me quotes for these figures
What you need before a quote
- Flat type, or condo and floor area
- What the contents would cost to replace
- What the renovation cost
- Age of the building, if you care about seepage tracing
- Whether you live there or rent it out
Other ways to compare in Singapore
- compareFIRST, the life-insurance shelf MoneySense points to. Direct Purchase plans there are commission-free up to the published cap.
- The insurer's own site, if you already know the product and want its illustration.
- A licensed insurance broker you choose. We do not name one and we do not publish a phone number for one.
- A bank that distributes the policy, if that is where you bank. Ask them what they are paid. We do not list a rate.
- The calculators on this site, which show a result before you send a form.
Questions on this topic
If I pay for the scratch myself, is my NCD safe?
Not if you were obliged to report and did not. GIA says failing to report can dock the discount at renewal, and can let the insurer refuse the claim or the next policy. Ask before you settle quietly.
When does the discount actually change?
At renewal, not the day of the crash. The table describes the renewal entitlement after a claim in the year.
What if both drivers are partly at fault?
GIA's safe harbour is being found totally not at fault in an accident involving another vehicle. Anything short of that may affect the discount. The insurer decides on the facts.
Does a protector change the morning after the crash?
No. It changes the renewal percentage in the case the wording covers. The repair is the motor policy. The protector is next year's discount.
Is it free?
Yes. The calculators and guides are free. A result appears in your browser before anyone asks for a phone number. Sending the form, if you want quotes for those figures, does not add a fee on this website.
Will you call me?
Not because you opened a page. We contact you only if you send the form or message us. You can read every result with the form left blank.
How does this site work?
The page does the arithmetic in your browser from the rules and the numbers you type. If you ask for quotes, we use your name, number and those figures only to reply about that enquiry. We do not sell the list. Personal data is handled under Singapore's Personal Data Protection Act. We are not an insurer and this is not financial advice.
Get a personalised breakdown
The calculator above runs in the browser with no phone number. Leave your details only if you want quotes or an audit for the same figures.
Sources
Facts on this page were checked against these sources on 30 October 2026.
- GIA: No Claims Discount gia.org.sg, checked 30 October 2026
- GIA: Motor Claims Framework brochure gia.org.sg, checked 30 October 2026
Fact-checked against HDB, IRAS, CPF, MAS.
