Key takeaways
- Guaranteed benefits plus non-guaranteed bonuses.
- You bear the investment risk on the bonuses.
- Surrendering bonuses can pay less than the printed cash value.
- Non-participating whole life has no bonuses and no that risk.
The numbers
- Guaranteed slice
- In the contract
- Bonuses
- Not guaranteed
- Who bears the risk
- You
- Surrender of bonuses
- May be less than the headline cash value
- Non-participating alternative
- Guaranteed benefits only, no bonuses
The short answer
A participating whole life policy pays a guaranteed benefit and may pay bonuses from the insurer’s participating fund. MoneySense’s table is short. The premiums cost more than term. There is a cash value. You bear the investment risk on the non-guaranteed bonuses. Premiums are typically level.
The line that gets skipped is about surrender. The surrender value of those bonuses may be less than the total cash value printed for the policy. A number in a birthday letter and a number on a surrender quote are not always the same number.
Two columns, two promises
Read every illustration as two columns. The guaranteed column is the promise. The bonus column is a scenario the insurer calculated under stated assumptions. If you only remember one figure, remember the guarantee. The scenario can be revised down in a bad stretch for the fund. That revision is not a surprise. It is the definition of non-guaranteed.
Non-participating whole life and endowment policies are the contrast. Their cash value is guaranteed benefits only. There are no bonuses, and MoneySense lists investment risk as none on that guaranteed value. You pay for a plainer contract. Participating is the one you choose when you want the chance of bonuses and you can stand a year when the bonus is thin.
| Participating whole life | Non-participating whole life | |
|---|---|---|
| Guaranteed benefits | Yes | Yes |
| Bonuses | Yes, not guaranteed | No |
| Investment risk | You bear it, on the bonuses | None, on the guaranteed value |
| Premium versus term | Higher | Higher |
| Surrender | Bonus portion may be worth less than the headline | The guaranteed surrender value is the figure to read |
What to ask before you sign
Ask what was actually paid as a bonus in recent years, and whether those years are a promise. Ask for the guaranteed surrender value at the year you might need the money, not only at age 80. Ask whether a loan against the policy cuts the cover. None of those answers are on this page, because they are policy-specific.
The cash value page is the number itself. The whole life page is the Singapore shelf, including the S$400,000 Direct Purchase cap. The hub compares a participating premium with term only after you type both. We are not an adviser, and we will not forecast a bonus.
Send me quotes for these figures
What you need before a quote
- Flat type, or condo and floor area
- What the contents would cost to replace
- What the renovation cost
- Age of the building, if you care about seepage tracing
- Whether you live there or rent it out
Other ways to compare in Singapore
- compareFIRST, the life-insurance shelf MoneySense points to. Direct Purchase plans there are commission-free up to the published cap.
- The insurer's own site, if you already know the product and want its illustration.
- A licensed insurance broker you choose. We do not name one and we do not publish a phone number for one.
- A bank that distributes the policy, if that is where you bank. Ask them what they are paid. We do not list a rate.
- The calculators on this site, which show a result before you send a form.
Questions on this topic
Are reversionary bonuses locked in once declared?
Treat declared bonuses as subject to the policy. MoneySense still warns that the surrender value of bonuses may be less than the total cash value. Ask how a declared bonus behaves on surrender, in writing.
Why did this year's bonus fall?
Because it depends on the participating fund. A cut is the risk you accepted. It is not a breach of the guaranteed column.
Is a higher illustrated bonus a better policy?
Only if you believe the scenario and you have compared guarantees. Two illustrations at the same assumed rate can hide different guarantees.
Does term have a participating version I should want?
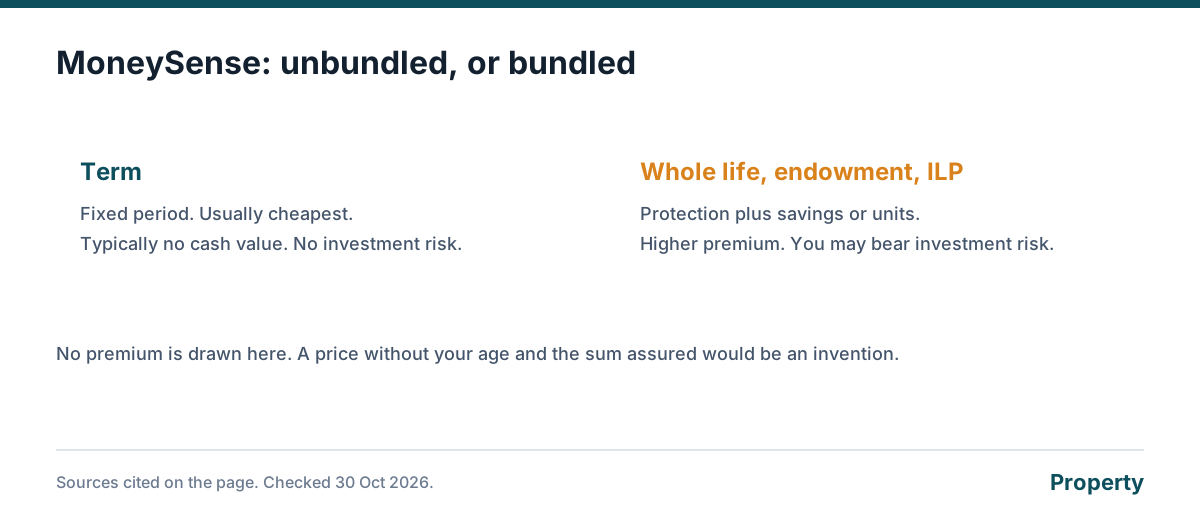
Term is the unbundled cover. It does not build this bonus. If you wanted the bonus, you wanted a bundle, and you should say so.
Is it free?
Yes. The calculators and guides are free. A result appears in your browser before anyone asks for a phone number. Sending the form, if you want quotes for those figures, does not add a fee on this website.
Will you call me?
Not because you opened a page. We contact you only if you send the form or message us. You can read every result with the form left blank.
How does this site work?
The page does the arithmetic in your browser from the rules and the numbers you type. If you ask for quotes, we use your name, number and those figures only to reply about that enquiry. We do not sell the list. Personal data is handled under Singapore's Personal Data Protection Act. We are not an insurer and this is not financial advice.
Get a personalised breakdown
The calculator above runs in the browser with no phone number. Leave your details only if you want quotes or an audit for the same figures.
Sources
Facts on this page were checked against these sources on 30 October 2026.
- MoneySense: Comparing term and bundled life insurance moneysense.gov.sg, checked 30 October 2026
Fact-checked against HDB, IRAS, CPF, MAS.
