Private-car discounts step 10, 20, 30, 40, 50 percent. One claim takes 50 to 20, 40 to 10, and 30 or less to 0. Two claims go to 0. Commercial vehicles and motorcycles top out at 20 percent and drop to 0 on one claim. GIA's protector example is a private car already at 50 percent: one claim stays at 50 percent with the same insurer, and is 20 percent with a new insurer. A wholly not-at-fault claim may not move the discount. The protector does not stop an insurer refusing renewal.
How we calculate
The pre-discount premium is your current premium divided by one minus the current NCD, unless you typed the 0% premium. One private-car claim maps 50% to 20%, 40% to 10%, and 30% or less to 0%. The headline is the extra premium while that discount climbs back, holding the base flat. A protector at 50% keeps 50% only on a same-insurer renewal.
Inputs
- Vehicle type
- Current NCD
- Premium you pay now or the premium at 0%
- Claims this year
- Protector add-on you type
Assumptions
- The base premium does not get loaded after a claim
- A wholly not-at-fault claim may not move the discount. The tool does not decide fault
- GIA's protector table is applied only to a private car at 50%
Constants and where they come from
| Constant | Value used | Source |
|---|---|---|
| Private-car scale and one-claim cut | 10/20/30/40/50. One claim: 50 to 20, 40 to 10, 30 or under to 0 | gia.org.sg |
On this page
Key takeaways
- Private-car no-claim discount runs 10%, 20%, 30%, 40%, then 50%.
- One claim cuts 50% to 20%. Two claims in the year cut it to zero.
- At 50%, a protector keeps 50% with the same insurer and leaves 20% if you switch.
- A claim you are wholly not at fault for may not move the discount.
The numbers
- Private car, 5 claim-free years
- 50% off the renewal premium
- One claim from 50%
- Renews at 20%
- One claim from 40%
- Renews at 10%
- One claim from 30% or less
- Renews at 0%
- Protector, same insurer, one claim at 50%
- Stays at 50%
- Protector, then a new insurer, one claim
- 20%, same as no protector
The short answer
An NCD protector is worth buying only when its price is smaller than the discount a claim would actually take, and only on the renewal path you will use. For a private car the General Insurance Association’s common scale is 10% after one claim-free year, then 20%, 30%, 40% and 50%. One claim cuts 50% to 20%, 40% to 10%, and 30% or anything lower to zero. Two or more claims in the same year cut the discount to zero.
The protector GIA describes is not a cheaper premium. It is an extra premium that, on a private car already at 50%, lets one claim renew at 50% with the same insurer. That same single claim, taken to a new insurer, is published at 20%. Two claims with the same insurer leave 20%. Three or more leave nothing. Commercial vehicles and motorcycles use a shorter scale, 10%, 15% and 20%, and one claim takes them to zero. GIA’s protector table is marked for private cars.
The calculator uses that scale and the premium you type. It does not invent a protector price, because GIA does not publish one.
Pages in this cluster
This guide is the hub. Each question below has its own page:
- ncd protector
- ncd protector singapore
- no claim discount
- ncd after accident
- lose ncd singapore
- ncd 50
- ncd protector worth it
- ncd transfer spouse
- ncd break in ownership
- protected ncd new insurer
Car policies that sit on this scale:
What one claim costs if the base premium stays flat
Suppose the premium before any discount is the number you type. A driver at 50% who claims once and has no protector renews at 20%, then can climb 30%, 40% and back to 50% over the following claim-free years. The discount given up is 30 percentage points, then 20, then 10. Added together, that is 60% of one year’s pre-discount premium, spread over three renewals.
That arithmetic is the scale. It is not a quote. Insurers also change the premium under the discount after a claim, and a wholly not-at-fault accident may not move the percentage at all. The calculator holds the base flat so you can see the discount on its own, then compare it with the add-on on your renewal invite.
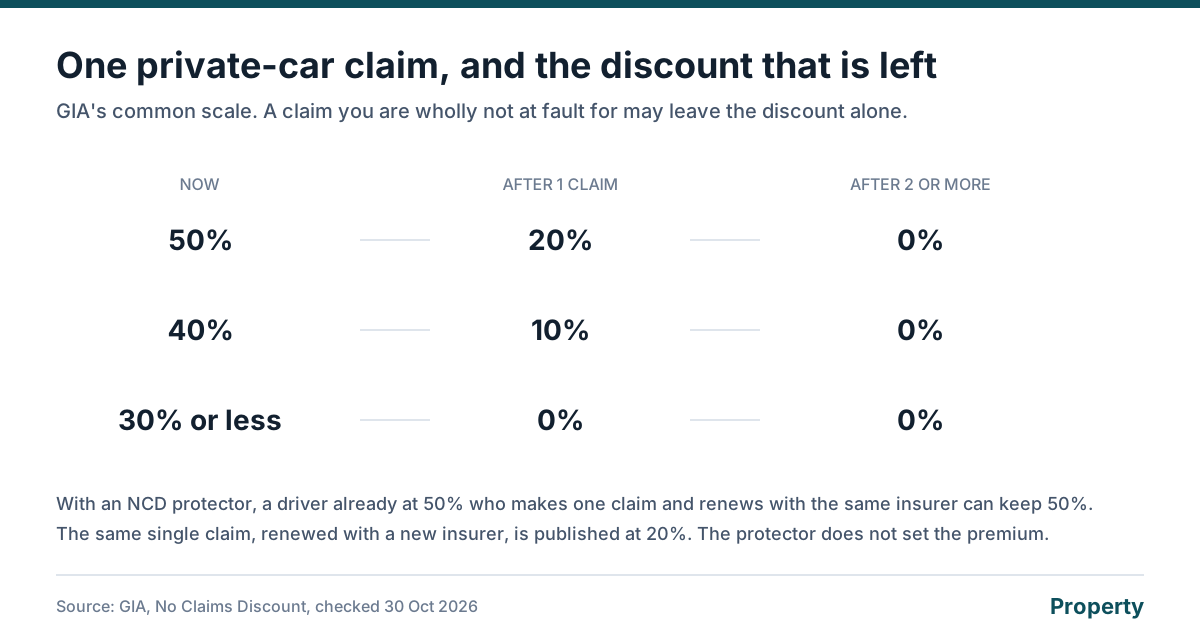
| Discount now | After 1 claim | After 2 or more claims |
|---|---|---|
| 50% | 20% | 0% |
| 40% | 10% | 0% |
| 30% or less | 0% | 0% |
Same insurer, or a new one
This is the part the add-on is easy to misunderstand. GIA’s protected scale, for a private car at 50%, is:
| Claims in the year | Renew with the same insurer | Renew with a new insurer |
|---|---|---|
| One | 50% | 20% |
| Two | 20% | 0% |
| Three or more | 0% | 0% |
One claim and a switch of insurer lands on 20%, which is where you would have landed with no protector. The add-on earns its keep when you stay, and when one claim is the risk you are buying down. It does not insure a second claim back to 50%, and it does not stop the insurer from declining renewal. Singlife’s own motor wording, covered on our car and EV page, is a separate point: without a protector, a claim there steps the discount down by 10 percentage points rather than the full GIA cut. Read the schedule you are actually buying. The PARF and loan-gap calculator is the other half of a total-loss question. The protector does not fill a loan gap.
What the discount is, and is not
The discount belongs to you, not to the car, but each car has its own record. Selling one car and buying another does not wipe it. Owning two cars does not let you paste 50% onto both. A transfer to a spouse stays inside the current insurer.
A break without a car is a matter of the insurer’s rule: often 24 months, sometimes 12. Report accidents within the policy’s window. GIA’s claims guide says a late report can cost you the cover, the discount, and the renewal.
We are not an insurer. The percentage is the published scale. The price is the quote.
What you need before a quote
- Your no-claim discount and the renewal premium
- The protector add-on from the invite, if you are pricing one
- COE date and outstanding loan, if you are testing a total loss
Other ways to compare in Singapore
- compareFIRST, the life-insurance shelf MoneySense points to. Direct Purchase plans there are commission-free up to the published cap.
- The insurer's own site, if you already know the product and want its illustration.
- A licensed insurance broker you choose. We do not name one and we do not publish a phone number for one.
- A bank that distributes the policy, if that is where you bank. Ask them what they are paid. We do not list a rate.
- The calculators on this site, which show a result before you send a form.
Questions on this topic
Do I lose my NCD if the accident was not my fault?
Not necessarily. GIA says the discount may be left alone if you are found totally not at fault in an accident with another vehicle. In other cases it may be cut. Ask the insurer before you assume either outcome. Failing to report an accident within the time on the policy can itself put the discount at risk.
Does the NCD protector stop my premium rising?
No. It protects the discount percentage in the case GIA publishes, which is a private car already at 50%. The insurer can still reprice the premium underneath that percentage, load the policy, or refuse to renew. GIA says a protector does not stop non-renewal or cancellation.
Can I take a protected NCD to another insurer?
GIA says the protected discount may not transfer. On the published 50% example, one claim renewed with a new insurer leaves 20%, which is the same cut as having no protector. Two claims leave nothing at the new insurer.
Can I give my NCD to my spouse?
Generally only to your spouse, and only with the current insurer. It does not follow you to a new insurer. It also does not apply to two cars at once. Each vehicle earns its own discount.
How long can I be without a car before the NCD expires?
GIA says most insurers keep it for a break of up to 24 months, and some set the limit at 12 months. Ask the insurer that holds the discount. There is no single statutory expiry.
Is it free?
Yes. The calculators and guides are free. A result appears in your browser before anyone asks for a phone number. Sending the form, if you want quotes for those figures, does not add a fee on this website.
Will you call me?
Not because you opened a page. We contact you only if you send the form or message us. You can read every result with the form left blank.
How does this site work?
The page does the arithmetic in your browser from the rules and the numbers you type. If you ask for quotes, we use your name, number and those figures only to reply about that enquiry. We do not sell the list. Personal data is handled under Singapore's Personal Data Protection Act. We are not an insurer and this is not financial advice.
Get a personalised breakdown
The calculator above runs in the browser with no phone number. Leave your details only if you want quotes or an audit for the same figures.
Sources
Facts on this page were checked against these sources on 30 October 2026.
- GIA: No Claims Discount gia.org.sg, checked 30 October 2026
- GIA: Motor Claims Framework brochure (reporting an accident) gia.org.sg, checked 30 October 2026
- Singlife motor insurance (10-point step-down where a protector is not taken) singlife.com, checked 30 October 2026
Fact-checked against HDB, IRAS, CPF, MAS.
