Key takeaways
- Silent schedule: treat the sport as excluded or capped.
- Amateur and professional are often different answers.
- A winter-sports option is not included because the trip is to Japan.
- We will not invent a depth or height limit the policy does not state.
The numbers
- If the policy is silent
- Do not assume cover
- Amateur versus professional
- Often treated differently
- Winter sports
- Usually an option or an exclusion
- Scuba, climb, motor sport
- Read the activity list
- A published universal height or depth
- None we will invent
The short answer
Adventure sports travel cover is a line on a schedule, not a mood. Insurers commonly exclude or limit winter sports, scuba diving, mountaineering, aerial activities and anything with a motor, or they cover an amateur version and exclude racing. The only safe reading of a silent policy is that the risky version is not covered. We will not print “scuba to 30 metres” or “ski off-piste is included” as if it were a national rule. Those numbers, when they exist, belong to one policy.
MSIG’s TravelEasy page points readers at the policy wording for exclusions, and it excludes travel against a government advisory. An activity can be excluded even when the country is not.
Separate the questions
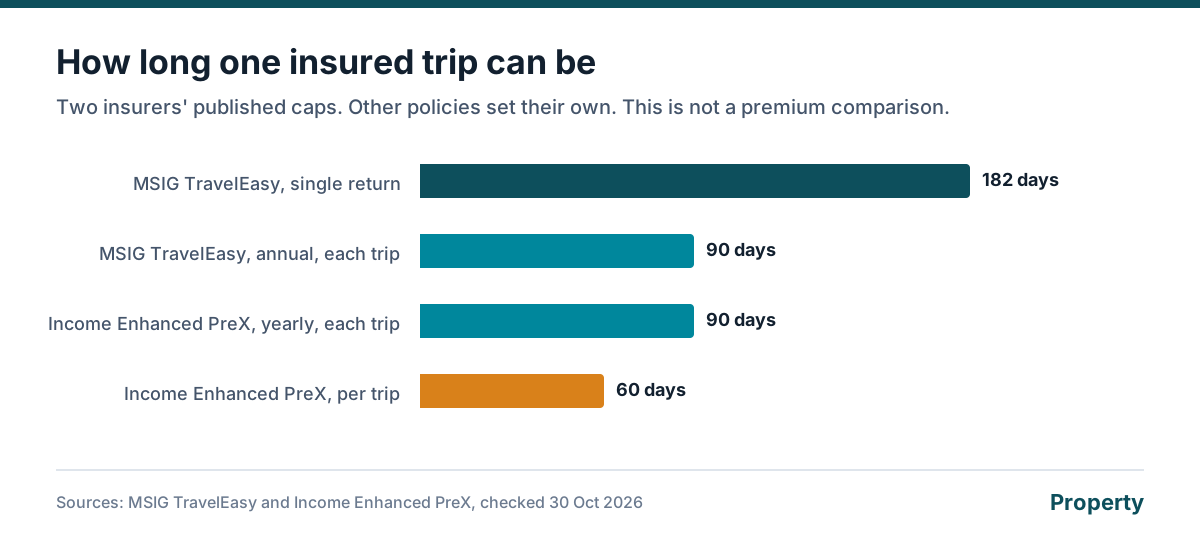
Whether you bought annual or single-trip does not add a sport. A 90-day cap still caps a ski season. A pre-existing condition is still excluded on a standard plan if you are hurt in a way the condition caused, and a fresh injury from an included sport is a different claim. Personal accident cover you hold in Singapore is not this policy. It may not follow you onto a mountain, and it is not evacuation. That difference is on the personal accident page.
| Activity habit | What to find before you pay |
|---|---|
| Resort skiing on marked runs | A winter-sports section, and whether off-piste is out |
| Diving | An amateur scuba section, and the depth or certification that policy uses |
| Climbing or trekking | Whether altitude, ropes or glaciers are out |
| A race or a paid guide trip you lead | The professional and competition exclusions |
| A jet-ski hour sold on the beach | Motor sports. Often excluded even when swimming is fine |
| Anything the government has advised against | MSIG excludes travel against that advisory |
If you cannot find the line
Buy a policy that prints it, or do not do the activity. A claims story that begins “I assumed” is not a section. Cruises with an excursion are the cruise page. The hub is the index. We are not an insurer, and we will not invent a height limit to make the table look complete.
Send me quotes for these figures
What you need before a quote
- Flat type, or condo and floor area
- What the contents would cost to replace
- What the renovation cost
- Age of the building, if you care about seepage tracing
- Whether you live there or rent it out
Other ways to compare in Singapore
- compareFIRST, the life-insurance shelf MoneySense points to. Direct Purchase plans there are commission-free up to the published cap.
- The insurer's own site, if you already know the product and want its illustration.
- A licensed insurance broker you choose. We do not name one and we do not publish a phone number for one.
- A bank that distributes the policy, if that is where you bank. Ask them what they are paid. We do not list a rate.
- The calculators on this site, which show a result before you send a form.
Questions on this topic
I only ski once a year. Am I an amateur?
You might be, on a policy that defines amateur as unpaid. A competition, even a small one, can fall outside that word. Read the definition.
Does annual cover include winter sports?
Not because it is annual. The option is separate from the choice between annual and single-trip.
What about a guided hike?
Guided does not mean covered. Altitude and climbing aids are the usual arguments. Find the activity, not the word guided.
If I am hurt doing an excluded sport, does medical cover still pay?
Often no. The exclusion can remove the medical section for that injury. That is why the activity line matters more than the headline medical limit.
Is it free?
Yes. The calculators and guides are free. A result appears in your browser before anyone asks for a phone number. Sending the form, if you want quotes for those figures, does not add a fee on this website.
Will you call me?
Not because you opened a page. We contact you only if you send the form or message us. You can read every result with the form left blank.
How does this site work?
The page does the arithmetic in your browser from the rules and the numbers you type. If you ask for quotes, we use your name, number and those figures only to reply about that enquiry. We do not sell the list. Personal data is handled under Singapore's Personal Data Protection Act. We are not an insurer and this is not financial advice.
Get a personalised breakdown
The calculator above runs in the browser with no phone number. Leave your details only if you want quotes or an audit for the same figures.
Foreign property is not regulated in Singapore the way a Singapore home is. This page is general information from Fiona Wang (Wang Ye), PropNex Realty Pte. Ltd. (CEA Reg. No. R068552B, agency licence L3008022J). It is not an offer. The CEA Practice Guidelines on the Marketing of Foreign Properties (PGMFP) apply. Confirm the developer's documents with a Malaysian conveyancing lawyer before you pay any fee.
Sources
Facts on this page were checked against these sources on 30 October 2026.
- MSIG: TravelEasy msig.com.sg, checked 30 October 2026
- MoneySense: insurance is the contract you bought, not the holiday you hoped for moneysense.gov.sg, checked 30 October 2026
Fact-checked against HDB, IRAS, CPF, MAS.
