Key takeaways
- Term: fixed period, usually the lower premium, no cash value.
- ILP: units, charges, and investment risk.
- A falling unit price can reduce cover if you do not top up.
- Do not buy an ILP because the term premium looked too cheap to be real.
The numbers
- Term cash value
- Typically none
- ILP value
- Units, after charges
- Who invests
- You do, if you buy term and invest the gap yourself
- ILP risk
- Yours
- Size the death benefit
- 9 times income is the MAS guide, either way
The short answer
ILP versus term is a category error if you only ask which is cheaper. Term insurance is a promise to pay a sum if you die, or are totally and permanently disabled, during a period you chose. It usually has no cash value. An investment-linked policy buys units and sells some of those units to pay for a promise and for fees. The leftover units are an investment you can lose.
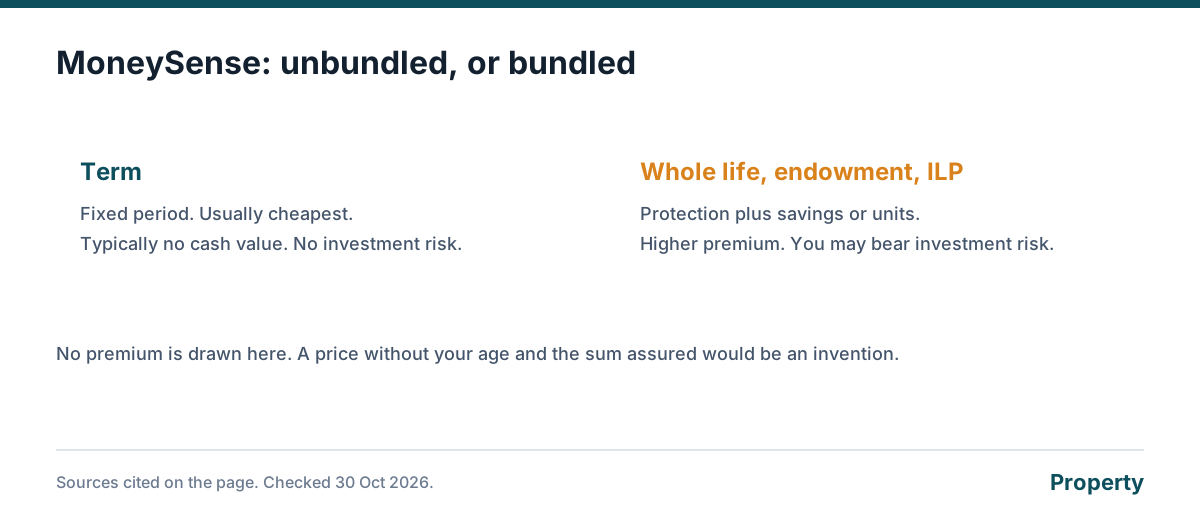
MoneySense puts term in the unbundled column and the ILP in the bundled column. Bundled costs more when the job was only protection. The ILP can be the right contract when you wanted the fund and you have read the charges.
Ask which sentence you meant
If the sentence was “if I die before the mortgage ends, pay it off”, that is term, or a mortgage policy. The sum should be large enough. Nine times annual income is the MAS guide for death and total permanent disability, on top of thinking about the loan separately when the loan is the debt.
If the sentence was “I want a fund and some insurance in the same debit”, that is an ILP, and the next page you need is the charge illustration, not a comparison site’s star rating. Units sold to pay for cover are explained on the ILP page.
| Term | ILP | |
|---|---|---|
| Pays on death in the period | Yes, the sum assured | Yes, according to the policy, which may be the higher of the sum assured and the units |
| Value if you live and walk away | Typically none | Whatever the units are worth that day |
| Market crash | Irrelevant to the sum assured | Can cut the value and, if charges continue, the sustainability of the cover |
| Your job | Keep paying for the term | Keep paying, and decide whether the fund still fits |
The honest calculator
The hub calculator will take an ILP premium and a term premium and invest the gap at a rate you type. That is not a model of unit cancellation. It will not tell you that a named fund returned a number we did not source. Use 0% if you only want to see the premiums. The buy term page is the habit of actually investing. We are not an adviser, and we will not rank ILP funds.
Send me quotes for these figures
What you need before a quote
- The product summary charge table and the latest statement
- Account value, the unit price date, and any surrender charge
- Whether you still need the death benefit, a critical illness rider, or other cover
- A replacement term quote, if you would buy cover again
- Fund factsheets for the sub-funds you actually hold
Other ways to compare in Singapore
- compareFIRST, the life-insurance shelf MoneySense points to. Direct Purchase plans there are commission-free up to the published cap.
- The insurer's own site, if you already know the product and want its illustration.
- A licensed insurance broker you choose. We do not name one and we do not publish a phone number for one.
- A bank that distributes the policy, if that is where you bank. Ask them what they are paid. We do not list a rate.
- The calculators on this site, which show a result before you send a form.
Questions on this topic
Can an ILP be cheaper than term?
Sometimes the first-year premium looks low. Look at charges over the years you will keep it, and at what happens to the units. A low start is not a low cost.
Does term have investment risk?
No. MoneySense lists investment risk as none for term. The risk is that the term ends or that you cannot renew it.
If I want both cover and funds, why not an ILP?
You can. The test is whether the bundled charges are acceptable versus buying term and a fund separately. This page cannot know your charges. The illustration can.
What happens in a bad market?
Term does not care about the market. An ILP's value does. If units are also paying the insurance, a long fall can threaten the cover unless you pay more.
Is it free?
Yes. The calculators and guides are free. A result appears in your browser before anyone asks for a phone number. Sending the form, if you want quotes for those figures, does not add a fee on this website.
Will you call me?
Not because you opened a page. We contact you only if you send the form or message us. You can read every result with the form left blank.
How does this site work?
The page does the arithmetic in your browser from the rules and the numbers you type. If you ask for quotes, we use your name, number and those figures only to reply about that enquiry. We do not sell the list. Personal data is handled under Singapore's Personal Data Protection Act. We are not an insurer and this is not financial advice.
Get a personalised breakdown
The calculator above runs in the browser with no phone number. Leave your details only if you want quotes or an audit for the same figures.
Sources
Facts on this page were checked against these sources on 30 October 2026.
- MoneySense: Comparing term and bundled life insurance moneysense.gov.sg, checked 30 October 2026
- MAS: Basic Financial Planning Guide mas.gov.sg, checked 30 October 2026
Fact-checked against HDB, IRAS, CPF, MAS.
