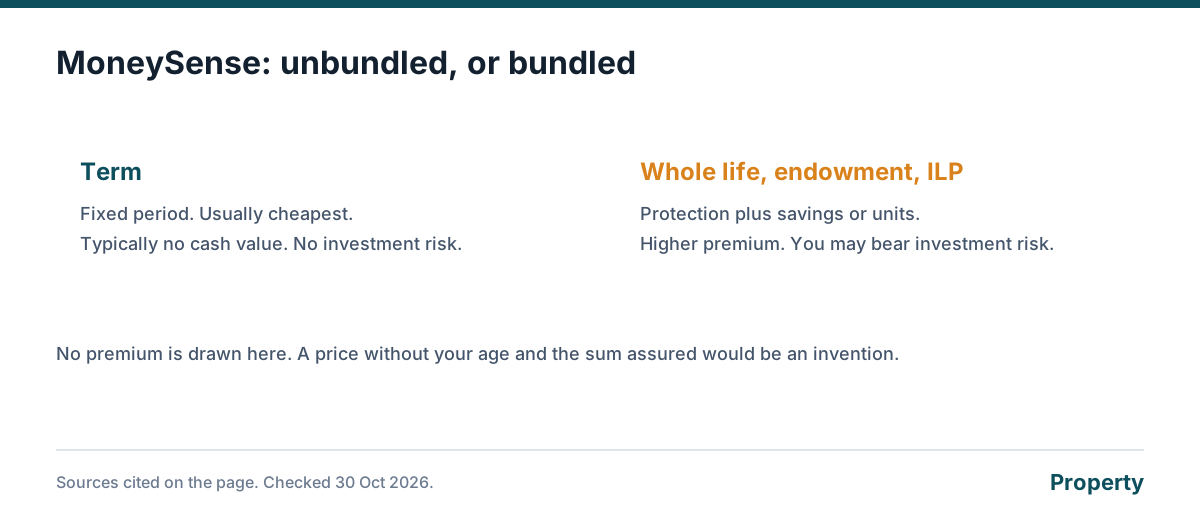
MoneySense: term cover is for a fixed period and usually costs less; whole life, endowment and ILP bundle protection with savings or investment, cost more, and the non-guaranteed part is investment risk you bear. This calculator compounds the premium gap once a year at the end of the year. It ignores taxes, fund fees beyond the premium you typed, and the chance you stop paying. A higher assumed return makes the invested pot larger. It does not make that return likely.
How we calculate
The gap is the bundled premium minus the term premium. It is saved at the end of each year. At 0% the pot is the gap times the years. Above 0% it is the ordinary future value of that annuity. The last tile subtracts a surrender value only if you typed one.
Inputs
- Annual term premium
- Annual bundled premium
- Years
- A return you choose
- Optional surrender value from an illustration
Assumptions
- 0% is the default and is not a forecast
- The return is yours, not an illustrated bonus
- Tax, lapses and charges outside the premium are ignored
Constants and where they come from
| Constant | Value used | Source |
|---|---|---|
| Why term is usually cheaper | MoneySense: term is unbundled and typically has no cash value | moneysense.gov.sg |
Key takeaways
- The strategy is a behaviour, not a product.
- If you do not invest the gap, you only bought less insurance.
- The term still has to be large enough for the years you need it.
- A 0% assumption shows the premiums. It is not a forecast.
The numbers
- Term
- Pays only if the insured event happens in the period
- The rest
- The premium you did not pay to a bundled policy
- If you spend the rest
- You are uninsured for that amount and not invested
- MAS size
- 9 times income for death and TPD
- Our default return
- Whatever you type, including zero
The short answer
Buy term and invest the rest is a sentence about behaviour. You buy term insurance for the years someone depends on you, because it is usually cheaper. You invest the premium you did not hand to a whole life or ILP policy. If you skip the investing, the strategy did not happen. You simply hold less insurance.
MoneySense’s facts underneath the slogan: term has a fixed period, usually costs less, and typically has no cash value and no investment risk. Whole life and other bundles cost more because they contain savings or investment, and you bear the risk on anything that is not guaranteed.
The three ways the slogan fails
First, the term is too small. The MAS guide uses 9 times annual income for death and total permanent disability. A tiny term plan plus a brokerage account does not feed a family. Size the sum on the gap calculator before you celebrate a low premium.
Second, the money is not invested. It is spent, or it sits in a salary account. At that point the whole life policy’s cash value, however imperfect, was a forced saving the slogan did not replace.
Third, you outlive the need you thought was short. A 20-year term that ends while you still have a dependant is not a clever investment. It is a calendar error. Whole life, or a new term if you can still buy one, is the conversation you should have had.
| If this is true | The slogan is |
|---|---|
| The term sum covers the years of dependence | Doing the insurance job |
| The gap is invested in something you will not spend | Doing the saving job |
| The gap is spent | Just a smaller policy |
| You still need cover after the term | The wrong length |
| You cancel old cover before the new policy is issued | A gap, not a strategy |
Use zero percent on purpose
The calculator asks for both annual premiums and a return. Leave the return at 0% and you see the premiums you would have paid, with no fantasy growth. Type a return only as your assumption. It is not the insurer’s illustrated bonus and not a historical fund return. If you have a benefit illustration, paste the surrender value and look at the last tile. The difference page is the same arithmetic described as a formula. The hub is the cluster. We are not an adviser.
What you need before a quote
- Annual income and take-home pay
- Cover you already hold, including DPS if you are in it
- The two annual premiums, if you are comparing term with a bundle
- A surrender value copied from an illustration, if you have one
Other ways to compare in Singapore
- compareFIRST, the life-insurance shelf MoneySense points to. Direct Purchase plans there are commission-free up to the published cap.
- The insurer's own site, if you already know the product and want its illustration.
- A licensed insurance broker you choose. We do not name one and we do not publish a phone number for one.
- A bank that distributes the policy, if that is where you bank. Ask them what they are paid. We do not list a rate.
- The calculators on this site, which show a result before you send a form.
Questions on this topic
Is this always the smart choice?
No. It is smart when the term matches the need and the gap is actually invested. It is a mistake when you wanted lifelong cover and bought twenty years instead.
What should I invest in?
Something you understand and will not raid. This site does not pick a fund. The calculator only compounds the rate you type.
Do I cancel an old whole life policy to do this?
Only after you check the new term will be issued, including on health terms. Replacing cover you already have can open a gap the slogan does not mention.
Does CPF LIFE count as the rest?
CPF LIFE is retirement income from CPF savings. It is not the premium difference from a life policy, and it does not pay out if you die at 45.
Is it free?
Yes. The calculators and guides are free. A result appears in your browser before anyone asks for a phone number. Sending the form, if you want quotes for those figures, does not add a fee on this website.
Will you call me?
Not because you opened a page. We contact you only if you send the form or message us. You can read every result with the form left blank.
How does this site work?
The page does the arithmetic in your browser from the rules and the numbers you type. If you ask for quotes, we use your name, number and those figures only to reply about that enquiry. We do not sell the list. Personal data is handled under Singapore's Personal Data Protection Act. We are not an insurer and this is not financial advice.
Get a personalised breakdown
The calculator above runs in the browser with no phone number. Leave your details only if you want quotes or an audit for the same figures.
Sources
Facts on this page were checked against these sources on 30 October 2026.
- MoneySense: Comparing term and bundled life insurance moneysense.gov.sg, checked 30 October 2026
- MAS: Basic Financial Planning Guide mas.gov.sg, checked 30 October 2026
Fact-checked against HDB, IRAS, CPF, MAS.
