Key takeaways
- Lifelong cover, if you keep paying, plus a cash value.
- Participating bonuses can be cut. You bear that risk.
- DPI whole life is commission-free and capped at S$400,000 per insurer.
- A small whole life policy does not replace a large term need.
The numbers
- Cover
- Can remain for life while premiums are paid
- Cash value
- Yes. Guaranteed, plus bonuses if participating
- Investment risk
- On the non-guaranteed bonuses
- DPI cap
- S$400,000 sum assured per insurer
- Where to compare
- compareFIRST
The short answer
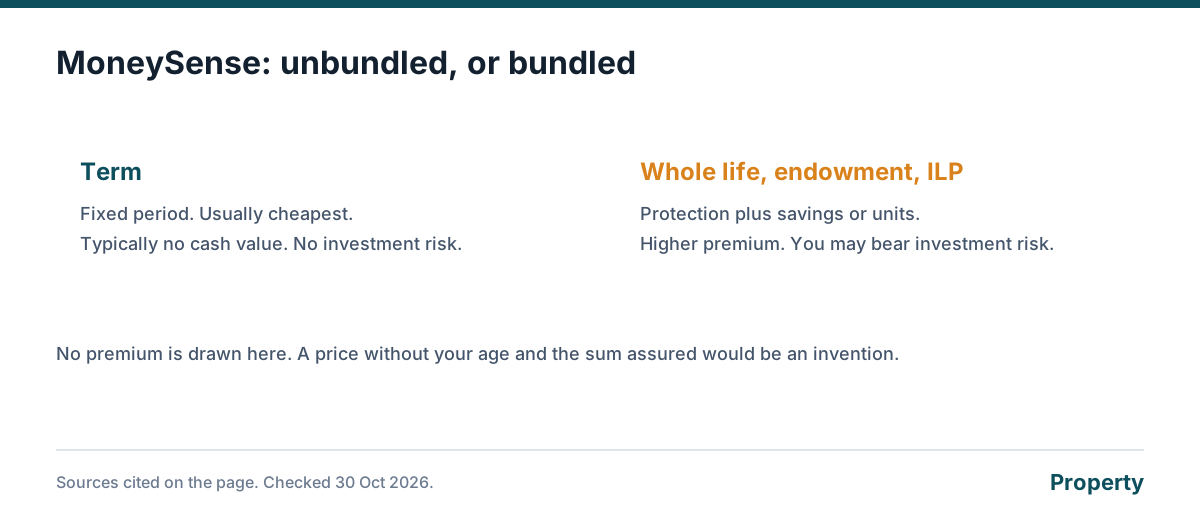
Whole life insurance in Singapore is a policy that can stay in force for your life, provided the premiums are paid, and that builds a cash value while it does. MoneySense groups it with the bundled products: more expensive than term, because protection and savings are sold together. If the policy participates in the insurer’s fund, the bonuses on top of the guaranteed benefit are not promised, and you bear that investment risk.
That is the product. It is not automatically the right product for a large family need. Term is usually cheaper for a big sum over a fixed period. The MAS guide still sizes death cover at 9 times income. A whole life premium that only buys a fraction of that, because it is also saving, leaves the income gap open.
The Singapore shelf
compareFIRST lists retail life policies so you can line up premiums and features, including whether critical illness is attached. MoneySense says not to buy on premium alone. Direct Purchase Insurance is the commission-free slice of that shelf. The sum assured caps at S$400,000 per insurer. On a term plan that includes critical illness, the CI benefit caps at S$200,000. You can buy from more than one insurer. Commission-free does not mean the premium above the cap is the lowest you will find.
| Piece | What to check on a Singapore whole life quote |
|---|---|
| How long it lasts | For life, while paid, or to a maturity age the contract names |
| Guaranteed cash value | The column that does not depend on bonuses |
| Bonuses | Whether it is participating, and that they are not guaranteed |
| Surrender | What you get if you stop in year 5 or year 10, not only at the end |
| DPI | Whether you are under the S$400,000 commission-free cap |
| The job | Lifelong cover and savings, not the entire 9 times income, unless you can afford that premium |
What it should not be asked to do
It should not be your emergency fund. Early surrender values are often poor. It should not be your CPF LIFE. Retirement income for life from 65 is the national annuity, with published anchors, on the CPF LIFE hub. It should not be the only cover on a parent of young children if the sum is small. The term comparison is that choice. Participating bonuses have their own page. Cash value, as a number, has its own page. The hub is the calculator. We do not publish a specimen premium. We are not an adviser.
Send me quotes for these figures
What you need before a quote
- Flat type, or condo and floor area
- What the contents would cost to replace
- What the renovation cost
- Age of the building, if you care about seepage tracing
- Whether you live there or rent it out
Other ways to compare in Singapore
- compareFIRST, the life-insurance shelf MoneySense points to. Direct Purchase plans there are commission-free up to the published cap.
- The insurer's own site, if you already know the product and want its illustration.
- A licensed insurance broker you choose. We do not name one and we do not publish a phone number for one.
- A bank that distributes the policy, if that is where you bank. Ask them what they are paid. We do not list a rate.
- The calculators on this site, which show a result before you send a form.
Questions on this topic
Does every whole life policy pay bonuses?
No. Participating policies do, and the bonuses are not guaranteed. Non-participating policies have guaranteed benefits only, and no bonuses.
Is Direct Purchase the cheapest whole life?
It removes commission, up to S$400,000 per insurer. Above the cap, or once you want features DPI does not offer, a normal policy can be cheaper or more expensive. Compare the illustration.
Should I buy whole life for a newborn?
Only if you want lifelong cover on the child and you accept the premium. It does not insure the parent's income. Term on the parent is the product that matches a lost salary.
Can I use the cash value while I am alive?
You can often surrender or, on some policies, borrow. Surrender can be less than the premiums paid, especially early. Read the guaranteed surrender column.
Is it free?
Yes. The calculators and guides are free. A result appears in your browser before anyone asks for a phone number. Sending the form, if you want quotes for those figures, does not add a fee on this website.
Will you call me?
Not because you opened a page. We contact you only if you send the form or message us. You can read every result with the form left blank.
How does this site work?
The page does the arithmetic in your browser from the rules and the numbers you type. If you ask for quotes, we use your name, number and those figures only to reply about that enquiry. We do not sell the list. Personal data is handled under Singapore's Personal Data Protection Act. We are not an insurer and this is not financial advice.
Get a personalised breakdown
The calculator above runs in the browser with no phone number. Leave your details only if you want quotes or an audit for the same figures.
Sources
Facts on this page were checked against these sources on 30 October 2026.
- MoneySense: Comparing term and bundled life insurance moneysense.gov.sg, checked 30 October 2026
- MoneySense: Insurance basics and compareFIRST moneysense.gov.sg, checked 30 October 2026
- compareFIRST comparefirst.sg, checked 30 October 2026
- MAS: Basic Financial Planning Guide mas.gov.sg, checked 30 October 2026
Fact-checked against HDB, IRAS, CPF, MAS.
