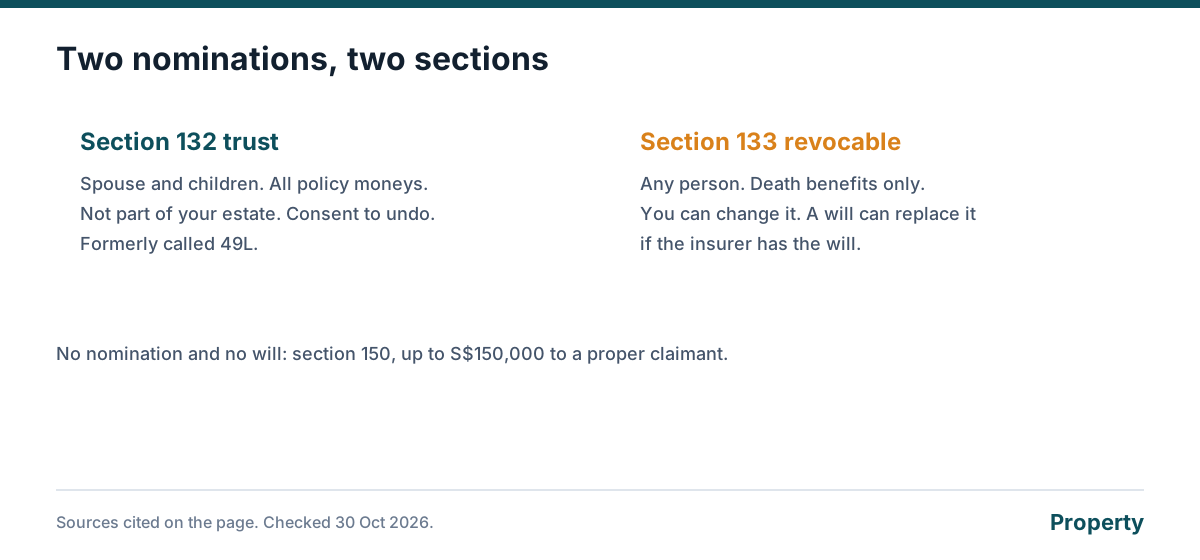
Insurance Act 1966 section 132 is the trust nomination. Section 133 is the revocable nomination. Section 132 used to be called 49L. LIA's 2026 guide: trust nominees can only be your spouse and/or children, you lose ownership, and revocation needs consent. Revocable nominations can name any person, pay death benefits only, and you can change them without consent. A will that the insurer knows about can replace a revocable nomination. It does not unwind a trust nomination on its own. With no nomination and no will, section 150 lets the insurer pay up to S$150,000 to a proper claimant. Trust nominations are not allowed on DPS, CPFIS, CPF retirement-sum annuities, ElderShield supplements, CareShield Life supplements or Integrated Shield Plans. This screen is not legal advice.
How we calculate
The screen applies section 132 or section 133 to those answers. It does not compute a premium.
Inputs
- Policy type
- Whether you are the owner and the life assured and at least 18
- Who should be paid
- Whether you will give the proceeds away
Assumptions
- This is not legal advice
- A trust form is refused for the plans LIA lists, including Integrated Shield and CareShield supplements
- With no nomination and no will, section 150 is the S$150,000 proper-claimant cap
Constants and where they come from
| Constant | Value used | Source |
|---|---|---|
| Trust and revocable nominations | Sections 132 and 133 | sso.agc.gov.sg |
| Proper claimant cap | S$150,000 | lia.org.sg |
Key takeaways
- Any nominee, not only spouse and children.
- Death benefits only. Critical illness stays with you.
- You can revoke it without their consent.
- A will the insurer has can replace it. It does not unwind a trust.
The numbers
- Section
- 133
- Nominees
- Any person
- What they receive
- Death benefits only
- Living benefits
- Still yours
- Change it
- Without the nominees' consent
The short answer
A revocable nomination is the form that keeps you in charge. Section 133 lets a policy owner who is at least 18 name anyone as a beneficiary of the death benefits, in the manner MAS prescribes, for 100% of those death benefits. You can revoke it without the nominees’ consent. Living benefits, including a critical illness claim, are paid to you. When you die, the death benefit goes to the people on the form.
It is the right form when the nominees are not only a spouse and children, or when they are, but you refuse to give the policy away. A trust is the form that gives it away. Do not file a trust because someone called both of them “a nomination”.
How it ends
You can file a new revocable form, or a new trust form, and the new one replaces the old revocable nomination. You can also revoke it by a will, in LIA’s 2026 account, when the will disposes of all the death benefits, specifies the policy, and the insurer knows. The latest instrument the insurer has is the one it pays on. Send the document. Do not assume the lawyer’s file is the insurer’s file.
If the only nominee dies before you, the nomination is revoked. If one of several dies, the survivors take that share in the proportions the regulations describe. It does not fall into the dead nominee’s estate the way a trust share can.
| Event | Revocable nomination |
|---|---|
| You change your mind | File a new form. No consent needed |
| You make a trust nomination later | The trust replaces it, and you have now given the policy away |
| A will the insurer has deals with this policy | It can replace the revocable nomination |
| A will tries to undo a trust | It does not. Trusts need the section 132 consent |
| One of several nominees dies | Survivors absorb the share |
| The only nominee dies | The nomination is revoked |
Online, and the policies that do not fit
Since 2 January 2024, insurers may offer online witnessing or an online attestor, with a secure electronic signature. Ask whether your policy is in that programme. LIA’s guide is more cautious about the trust form. CPF retirement-sum annuities allow neither kind of nomination. DPS and CPFIS are out for trusts because you must keep control. The trust page is that refusal. The will page is the instrument question. The hub is the index. We are not lawyers.
What you need before a quote
- Whether you are the owner and the life assured, and at least 18
- Who should receive the money
- Whether you are willing to give the policy away
- The policy type. Some plans cannot take a trust nomination
Other ways to compare in Singapore
- compareFIRST, the life-insurance shelf MoneySense points to. Direct Purchase plans there are commission-free up to the published cap.
- The insurer's own site, if you already know the product and want its illustration.
- A licensed insurance broker you choose. We do not name one and we do not publish a phone number for one.
- A bank that distributes the policy, if that is where you bank. Ask them what they are paid. We do not list a rate.
- The calculators on this site, which show a result before you send a form.
Questions on this topic
Can I name a friend or a parent?
Yes. The spouse-and-children limit is the trust nomination, not this one.
Does my critical illness payout go to them?
No. LIA says living benefits are paid to you. On your death, the remaining death benefit goes to the nominees.
What if my only nominee dies first?
The revocable nomination is revoked. If several were named and one dies, the survivors absorb that share in the proportions the rules set.
Will a new will cancel it?
LIA says a will can replace a revocable nomination if it deals with all the death benefits, identifies the policy, and the insurer knows about it. Tell the insurer. A will in a drawer is not notice.
Is it free?
Yes. The calculators and guides are free. A result appears in your browser before anyone asks for a phone number. Sending the form, if you want quotes for those figures, does not add a fee on this website.
Will you call me?
Not because you opened a page. We contact you only if you send the form or message us. You can read every result with the form left blank.
How does this site work?
The page does the arithmetic in your browser from the rules and the numbers you type. If you ask for quotes, we use your name, number and those figures only to reply about that enquiry. We do not sell the list. Personal data is handled under Singapore's Personal Data Protection Act. We are not an insurer and this is not financial advice.
Get a personalised breakdown
The calculator above runs in the browser with no phone number. Leave your details only if you want quotes or an audit for the same figures.
Sources
Facts on this page were checked against these sources on 30 October 2026.
- Insurance Act 1966, section 133 and the nomination provisions sso.agc.gov.sg, checked 30 October 2026
- LIA: Your Guide to the Nomination of Insurance Nominees, 2026 lia.org.sg, checked 30 October 2026
- MAS: online nomination from 2 January 2024 mas.gov.sg, checked 30 October 2026
Fact-checked against HDB, IRAS, CPF, MAS.
