Key takeaways
- Minimum cover is EUR 30,000.
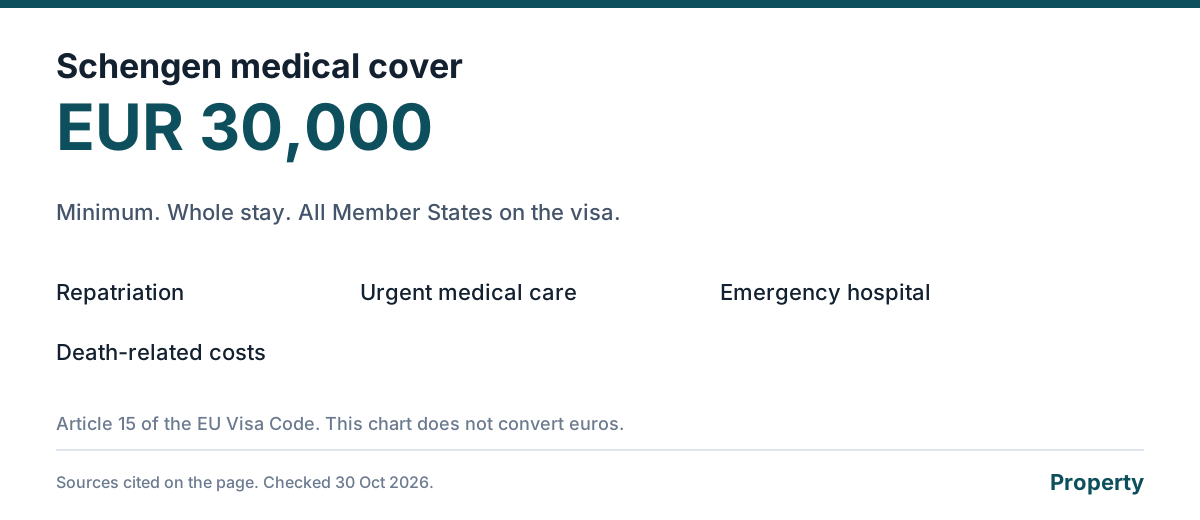
- It must include repatriation, urgent care, emergency hospital treatment and death.
- It must last the whole stay and apply in the Member States.
- A multiple-entry visa proves insurance for the first visit.
The numbers
- Minimum
- EUR 30,000
- Must include
- Repatriation, urgent care, emergency hospital, death
- Geography
- The Member States on the visa
- Duration
- The entire intended stay
- Multiple-entry
- Proof for the first intended visit
The short answer
Schengen travel insurance means the medical policy a short-stay visa application has to show. Article 15 of Regulation (EC) No 810/2009 says applicants for a uniform visa of one or two entries must have adequate travel medical insurance for any expenses from repatriation for medical reasons, urgent medical attention, emergency hospital treatment, or death, during the stay. The insurance is valid throughout the Member States, covers the entire intended stay or transit, and the minimum coverage is EUR 30,000.
For a multiple-entry visa you prove cover for the first intended visit, and you acknowledge you need it for later stays. Applicants should, in principle, buy it in their country of residence.
What the certificate has to say
A holiday policy can fail this test while looking expensive. Cancellation, baggage and a missed connection do not replace repatriation. A medical limit stated only in Singapore dollars has to be shown to meet EUR 30,000, not assumed. Cover that starts the day after you land, or ends before the visa does, fails the “entire stay” line. Cover that excludes the country you will spend the week in fails the territory line.
| Article 15 piece | Pass | Fail |
|---|---|---|
| Amount | At least EUR 30,000 | A lower limit, or a dollar figure you have not tied to euros |
| Benefits | Repatriation, urgent care, emergency hospital, death | Cancellation only |
| Dates | The whole stay you declared | A weekend policy for a ten-day visa |
| Place | The Member States concerned | A policy that leaves out the country of entry |
| When you show it | With the application, for one or two entries | After you have already been refused for not having it |
Annual plans and first entries
An annual policy can be the proof if the certificate covers the first visit’s dates and meets the euro minimum. It does not cover a later visit by magic. The regulation says you declare that you know you need insurance for those later stays. The annual page is the day cap. The single-trip page is one journey. The hub is everything that is not a visa rule. We do not convert EUR 30,000, and we are not a consulate.
Send me quotes for these figures
What you need before a quote
- Flat type, or condo and floor area
- What the contents would cost to replace
- What the renovation cost
- Age of the building, if you care about seepage tracing
- Whether you live there or rent it out
Other ways to compare in Singapore
- compareFIRST, the life-insurance shelf MoneySense points to. Direct Purchase plans there are commission-free up to the published cap.
- The insurer's own site, if you already know the product and want its illustration.
- A licensed insurance broker you choose. We do not name one and we do not publish a phone number for one.
- A bank that distributes the policy, if that is where you bank. Ask them what they are paid. We do not list a rate.
- The calculators on this site, which show a result before you send a form.
Questions on this topic
Is S$44,000 the same rule?
No. The rule is EUR 30,000. A Singapore dollar estimate moves with the exchange rate. Do not put a converted figure on the visa form in place of the euro limit.
Does any Singapore travel plan qualify?
Only if the certificate shows at least EUR 30,000, the right benefits, the right dates and the right territory. Many plans are larger. Check the certificate, not the brand.
Can I buy it after the visa is granted?
You have to prove it with the application for a one or two-entry visa. Buy a policy that covers the stay you are declaring.
Are there exemptions?
Article 15 allows some professional cases, and holders of diplomatic passports are exempt. Assume you need the policy unless the consulate has told you that you do not.
Is it free?
Yes. The calculators and guides are free. A result appears in your browser before anyone asks for a phone number. Sending the form, if you want quotes for those figures, does not add a fee on this website.
Will you call me?
Not because you opened a page. We contact you only if you send the form or message us. You can read every result with the form left blank.
How does this site work?
The page does the arithmetic in your browser from the rules and the numbers you type. If you ask for quotes, we use your name, number and those figures only to reply about that enquiry. We do not sell the list. Personal data is handled under Singapore's Personal Data Protection Act. We are not an insurer and this is not financial advice.
Get a personalised breakdown
The calculator above runs in the browser with no phone number. Leave your details only if you want quotes or an audit for the same figures.
Sources
Facts on this page were checked against these sources on 30 October 2026.
- EU Visa Code, Article 15, consolidated eur-lex.europa.eu, checked 30 October 2026
Fact-checked against HDB, IRAS, CPF, MAS.
