MoneySense, updated 28 September 2026: disability income pays a fixed monthly amount if you cannot work because of illness or accident, up to 80% of average monthly salary, after a deferred period, and it stops or reduces when you can work again. The definition of disability is the insurer's. A personal accident plan is a different contract: it follows an accident schedule and does not replace income lost to illness. Total and permanent disability on a life policy is a lump sum under that policy's definition, not this monthly benefit. We do not price either product.
How we calculate
Months of salary equal the lump sum divided by salary. The 80% line is 0.8 times salary. A monthly benefit above that line is flagged. The full-term figure is the monthly benefit times 12 times the years you typed.
Inputs
- Monthly salary
- Personal accident lump sum
- Disability income per month
- Deferred period and benefit years
Assumptions
- 80% is MoneySense's ceiling, not the benefit you will be offered
- The lump sum is accident-only
- Recovery can stop the monthly benefit before the term you typed
Constants and where they come from
| Constant | Value used | Source |
|---|---|---|
| 80% ceiling | Up to 80% of average monthly salary | moneysense.gov.sg |
On this page
Key takeaways
- Up to 80% of average monthly salary, not the whole salary.
- Payment starts after the deferred period, if you are still disabled.
- It can run 5 or 10 years, or to 60 or 65, then stops or reduces when you work again.
- The definition of disability is the insurer's, and it changes the premium.
The numbers
- Ceiling
- Up to 80% of average monthly salary
- Starts
- After the deferred period
- Typical duration
- 5 or 10 years, or to 60 or 65
- Stops
- When you can work, sometimes in proportion
- Not the same as
- A personal accident lump sum
The short answer
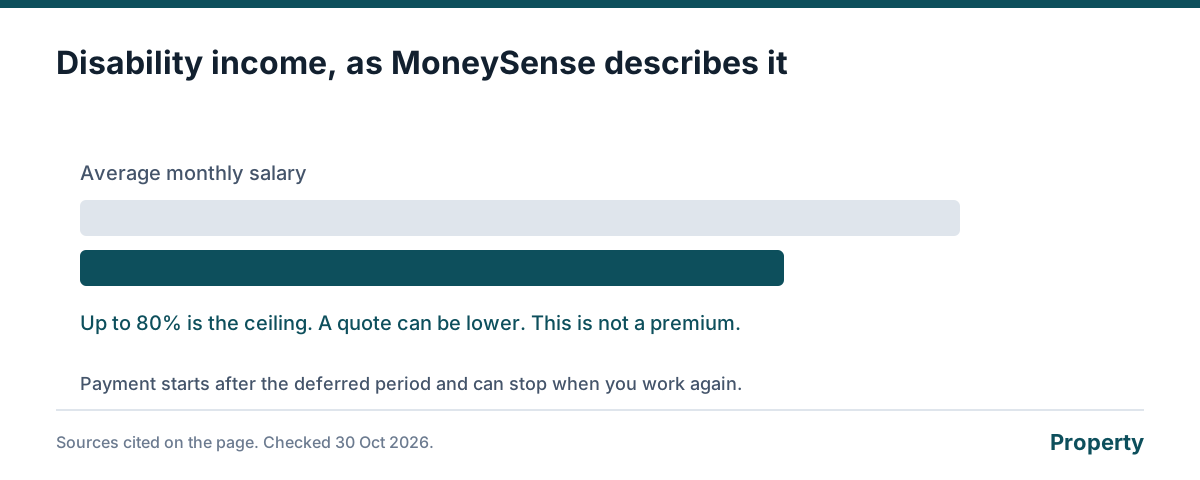
Disability income insurance in Singapore pays you a monthly amount if illness or injury stops you working. MoneySense, updated 28 September 2026, says that amount is up to 80% of your average monthly salary, not the whole salary. It starts only if you are still disabled after a deferred period. It may be paid for up to 5 or 10 years, or until you are 60 or 65. It stops or reduces when you can work again, sometimes in proportion to the recovery.
The definition of disability is the insurer’s. Two quotes with the same monthly benefit can be different claims. Ask which definition you are paying for.
The calculator sets a benefit you type against 80% of a salary you type. It does not invent a premium.
The wait is part of the price
A 90-day or six-month deferred period is a stretch of no income from the policy while you are already off work. Emergency savings cover that stretch. If they do not, a shorter wait may be worth a higher premium. We will not tell you which wait is standard, because MoneySense says the waits differ.
| Piece | MoneySense’s description |
|---|---|
| How much | Up to 80% of average monthly salary |
| When it starts | After the deferred period, if you are still disabled |
| How long | Up to 5 or 10 years, or to 60 or 65 |
| When it ends early | When you can work again. The cut may track the recovery |
| What changes the premium | The disability definition, among other things |
What people buy instead, by mistake
A personal accident lump sum does not pay a salary, and it does not pay for illness. Hospital cash pays a fixed sum per day in a ward, which may not match the bill and is not a salary. CareShield pays for severe disability measured in daily activities, not for being unable to do your job. Total and permanent disability on a life policy is a lump sum under a strict test. The TPD page keeps that lump sum apart from this monthly benefit. The income protection page is the gap during the wait and after you return part-time. The hub links them. We are not an insurer.
Listicles
Numbered checks for this cover. They do not rank insurers.
| Page | What it is |
|---|---|
| 10 Questions to Ask About Disability Income Insurance | A list, not a premium table |
| 10 Signs Your Income Is Not Insured | A list, not a premium table |
What you need before a quote
- Average monthly salary
- The personal accident lump sum on the schedule
- The disability income benefit per month, the wait, and how many years it can run
Other ways to compare in Singapore
- compareFIRST, the life-insurance shelf MoneySense points to. Direct Purchase plans there are commission-free up to the published cap.
- The insurer's own site, if you already know the product and want its illustration.
- A licensed insurance broker you choose. We do not name one and we do not publish a phone number for one.
- A bank that distributes the policy, if that is where you bank. Ask them what they are paid. We do not list a rate.
- The calculators on this site, which show a result before you send a form.
Questions on this topic
Why not 100% of salary?
MoneySense says the policy helps with the loss and will not completely replace income. The published ceiling is 80% of average monthly salary.
What is a deferred period?
The months at the start of the disability when nothing is paid. Your savings have to cover that wait. The policy will not.
Own occupation or any occupation?
MoneySense says definitions differ and the premium depends on the definition. We will not pretend one definition is the market default. Ask which word is in the quote.
Is a quote above 80% a win?
It is a reason to ask what will actually be issued. The calculator flags a monthly benefit above 80% of the salary you typed.
Is it free?
Yes. The calculators and guides are free. A result appears in your browser before anyone asks for a phone number. Sending the form, if you want quotes for those figures, does not add a fee on this website.
Will you call me?
Not because you opened a page. We contact you only if you send the form or message us. You can read every result with the form left blank.
How does this site work?
The page does the arithmetic in your browser from the rules and the numbers you type. If you ask for quotes, we use your name, number and those figures only to reply about that enquiry. We do not sell the list. Personal data is handled under Singapore's Personal Data Protection Act. We are not an insurer and this is not financial advice.
Get a personalised breakdown
The calculator above runs in the browser with no phone number. Leave your details only if you want quotes or an audit for the same figures.
Sources
Facts on this page were checked against these sources on 30 October 2026.
- MoneySense: Understanding disability income insurance, updated 28 September 2026 moneysense.gov.sg, checked 30 October 2026
- MoneySense: Understanding health insurance moneysense.gov.sg, checked 30 October 2026
Fact-checked against HDB, IRAS, CPF, MAS.
