On this page
Key takeaways
- 1.24% was the 3-month compounded SORA on 15 October 2026, down from 2.90% at the end of January 2025.
- 1.65% to 1.80% was the range of two-year fixed rates brokers listed on 6 October 2026, for HDB flats and completed condos.
- 0.20% to 0.30% over 3-month SORA was the lowest floating spread listed, or about 1.44% to 1.54% all in.
- 2.6% is the HDB concessionary loan rate from 1 October to 31 December 2026; CPF Board kept it unchanged in its 22 September 2026 announcement.
The numbers
- 3-month compounded SORA
- 1.24% on 15 October 2026
- Two-year fixed, broker-listed
- About 1.65% to 1.80% (6 October 2026)
- Lowest floating spread
- 3M SORA + 0.20% to 0.30%
- HDB concessionary loan
- 2.6% a year (October to December 2026)
- Checked
- 19 October 2026, updated monthly
Where buyers get stuck
The tables on this page are a record of October 2026. They are not a live SORA feed and they are not a bank offer you can accept now. 3-month compounded SORA was 1.24% on 15 October 2026, against 3.38% at the end of October 2024. Broker lists gathered in early October 2026 showed two-year fixed rates of about 1.65% to 1.80% and floating rates of SORA plus 0.20% to 0.30%. The HDB concessionary rate of 2.6% is CPF Board’s figure for 1 October to 31 December 2026, not a lifetime price. How a reset actually works is in the fixed and SORA guide. Whether to switch is in the refinance guide.
We checked the figures below on 19 October 2026. Broker prices depended on loan size. Treat them as what was listed that month, not as a quote. We are not a bank or a licensed adviser.
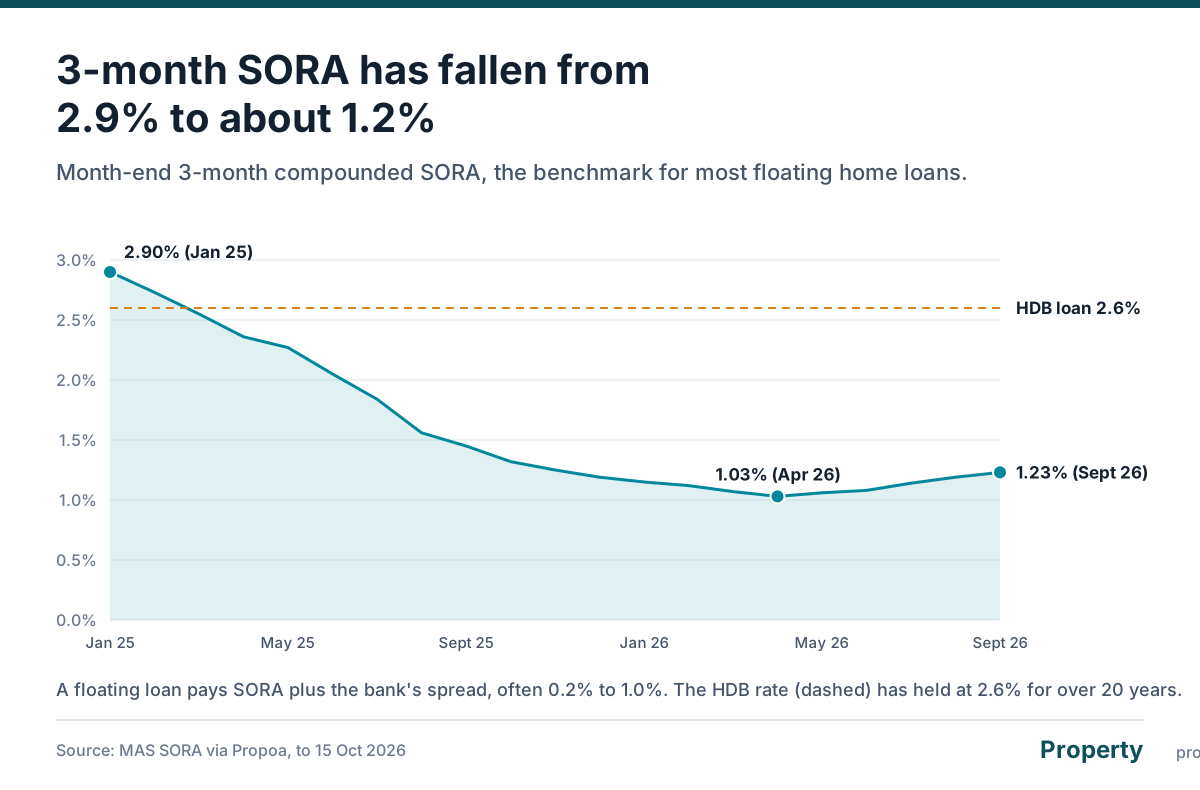
3-month compounded SORA through 15 October 2026
SORA fell through 2025, bottomed in April 2026 and had edged up by mid-October 2026. These are month-end figures as MAS published them, reproduced by Propoa. The last value stored on this page is 1.24% on 15 October 2026. It matched HousingLoanSG and Nexus Mortgage when it was checked. It is not a claim about any later day.
| Month end | 3M compounded SORA |
|---|---|
| October 2026 (to 15 Oct) | 1.24% |
| September 2026 | 1.23% |
| August 2026 | 1.19% |
| July 2026 | 1.14% |
| June 2026 | 1.08% |
| May 2026 | 1.06% |
| April 2026 | 1.03% |
| March 2026 | 1.07% |
| February 2026 | 1.12% |
| January 2026 | 1.15% |
| December 2025 | 1.19% |
| October 2025 | 1.32% |
| July 2025 | 1.84% |
| April 2025 | 2.36% |
| January 2025 | 2.90% |
Because the 3-month figure is an average of the past three months, it lags the overnight rate. A floating loan’s rate resets every three months, so the October number tells you roughly what borrowers will pay over the next quarter.
Latest home loan packages
The first table shows the lowest prices brokers listed in that October 2026 snapshot. PropertyNet’s figures are dated 6 October 2026 and were indicative for a S$1 million loan. Floating rates in the table were worked out at the 15 October 2026 3-month compounded SORA of 1.24%, not at a later print.
| Bank | Type | Property | Rate in year 1 |
|---|---|---|---|
| Hong Leong Finance | 2-year fixed | HDB | 1.65% |
| Standard Chartered | 2-year fixed | Completed condo | 1.70% |
| DBS | 2-year fixed | Completed condo | 1.73% |
| UOB | 2-year fixed | HDB or completed condo | 1.75% |
| DBS | 2-year fixed | HDB | 1.80% |
| HSBC | 3M SORA + 0.20% | Completed condo | About 1.44% |
| Maybank | 3M SORA + 0.20% | Completed condo | About 1.44% |
| Standard Chartered | 3M SORA + 0.25% | Completed condo | About 1.49% |
| UOB | 3M SORA + 0.25% | HDB | About 1.49% |
| DBS | 3M SORA + 0.28% | New launch, under construction | About 1.52% |
| OCBC | 3M SORA + 0.30% | HDB | About 1.54% |
Prices quoted on a S$500,000 loan were higher. The Straits Times reported on 2 October 2026, in figures summarised by Tribe SG, that Standard Chartered had raised its one-year and two-year fixed rates to 2.00% from 1 October. OCBC quoted 2.08% for three years fixed and 2.28% for an HDB five-year fixed. DBS quoted 2.08% for an HDB three-year fixed, Citi 2.20% for two years and Maybank 2.55% for three years.
Bank websites show a third set of prices. These are the standard packages anyone can apply for, and they are well above what brokers report.
| Bank | Published package | Minimum loan |
|---|---|---|
| Maybank | 2-year fixed at 3.30%, 3-year fixed at 3.75% | S$100,000 |
| Maybank | 3M SORA + 0.70% for 3 years, 2-year lock-in | S$100,000 |
| DBS | 3M SORA + 0.75%, 2-year lock-in, part of a fixed and floating split | Not stated |
| OCBC | 1M SORA + 0.98% for 2 years, then + 1.40% | S$100,000 |
| Standard Chartered | 3M SORA + 1.00%, 2-year lock-in | S$100,000 |
| HSBC | Premier rates from 1.54%, type not stated | S$900,000 |
UOB and CIMB did not publish home loan rates on their websites when we checked.
How to read fixed vs floating
A fixed package locks your rate for the fixed period, often two or three years, and then follows the formula in the letter. In the October 2026 snapshot, Maybank’s two-year fixed moved to one-month SORA plus 1.00% from year three, which was about 2.30% using the 1.30% one-month print from 15 October 2026. That arithmetic is tied to that day. The fixed and SORA guide explains the reset without treating an old print as the rate you will be offered.
A floating package charges SORA plus a spread. The spread is set in your letter of offer, but SORA moves every quarter. On a S$600,000 loan over 20 years, 1.44% costs about S$2,879 a month. If SORA rose by one percentage point, the same loan at 2.44% would cost about S$3,162, or S$283 more.
Loan size changes the choice. Tribe SG worked out that for loans of S$1 million or more, broker-priced fixed rates were only about 0.02 percentage points above floating in October 2026. For a S$500,000 loan the gap was about 0.30 points, so fixing cost more.
Look past the year 1 rate. Compare the spread in years 2 and 3, the lock-in, the penalty for leaving early, which is about 1.5% of the loan for most banks, and any clawback of subsidised legal fees.
When refinancing pays
Refinancing is worth checking when your lock-in is ending or your rate has reverted to a higher one. Here is a worked example.
A couple owe S$600,000 with 20 years left and pay 3.00% after their package reverted. That is about S$3,328 a month. A new two-year fixed at 1.75% brings it to about S$2,965, a saving of S$363 a month or about S$8,700 over the two years. If legal and valuation fees came to S$3,000 and the new bank did not cover them, the switch would pay for itself in about nine months.
It rarely pays inside a lock-in. A 1.5% penalty on S$600,000 is S$9,000, more than two years of savings in this example.
HDB borrowers face a one-way choice. On a S$400,000 loan over 25 years, HDB’s 2.6% costs about S$1,815 a month and a 1.80% bank rate about S$1,657. You save S$158 a month, but you cannot move back to an HDB loan later. Our HDB loan vs bank loan guide covers the rest.
Run your own numbers in the refinancing calculator, or use the mortgage calculator if you are buying.
How we track these rates
We update this page once a month, and sooner if SORA moves sharply or a major bank changes its packages. Each update rechecks SORA against MAS’s published figures, the HDB rate against CPF Board’s quarterly announcement, each bank’s own website and at least two broker comparison pages. Where a bank does not publish a rate, we say so instead of guessing. Next update: November 2026.
Questions on this topic
What is the SORA rate today?
This page does not publish a live SORA print. The last 3-month compounded figure stored here is 1.24% on 15 October 2026. One-month compounded SORA was 1.30% on the same day. MAS publishes each business day's figure the next business day. Read MAS for a later print, and read your letter for the rate you actually pay.
What is a good home loan rate in Singapore right now?
This page cannot say. The lists below are what brokers published in early October 2026: two-year fixed packages from about 1.65% to 1.80%, and floating packages at 3-month SORA plus 0.20% to 0.30%, which was about 1.44% to 1.54% at the 15 October print. They are not offers you can accept now. Ask a bank for a current letter.
Is a fixed or floating home loan better in 2026?
It depends on how much a rise in your instalment would hurt. In October 2026 the cheapest floating packages were only a few hundredths of a percentage point below the cheapest fixed ones for large loans, so many borrowers chose to fix. For loans under S$500,000 the gap was wider, at around 0.30 to 0.50 percentage points.
Why are the rates on bank websites higher than the ones brokers quote?
Banks publish standard packages and keep their best prices for quotes. Maybank's website showed a two-year fixed rate of 3.30% on 19 October 2026, while brokers were listing bank fixed rates below 2%. Ask for a written quote and compare it with a broker's before you sign.
Should I switch from an HDB loan to a bank loan?
Only if the saving is worth giving up the HDB loan for good, because HDB will not take you back. On a S$400,000 loan over 25 years, 2.6% costs about S$1,815 a month and 1.80% about S$1,657. The bank rate can rise after the lock-in, while CPF Board kept the HDB rate at 2.6% for October to December 2026.
Get a personalised Singapore shortlist and financing check
Share your budget and what you're comparing. We'll reply on WhatsApp with matching units, recent caveats and your exact cash/CPF breakdown.
Sources
Facts on this page were checked against these sources on 8 November 2026.
- Propoa: 3-month compounded SORA, month-end history from MAS data, checked 19 Oct 2026 propoagroup.co, checked 8 November 2026
- MAS: Domestic interest rates (SORA and compounded SORA) eservices.mas.gov.sg, checked 8 November 2026
- HousingLoanSG: Latest SORA rates (3M compounded SORA 1.24180 on 15 Oct 2026), checked 19 Oct 2026 housingloansg.com, checked 8 November 2026
- Nexus Mortgage: SORA rate today, checked 19 Oct 2026 nexusmortgage.sg, checked 8 November 2026
- CPF Board: Interest rates from 1 October to 31 December 2026 (22 Sep 2026) cpf.gov.sg, checked 8 November 2026
- PropertyNet: Latest bank mortgage rates in Singapore (6 Oct 2026), checked 19 Oct 2026 propertynet.sg, checked 8 November 2026
- Tribe SG: Certainty premium depends on loan size (October 2026), checked 19 Oct 2026 tribesg.com, checked 8 November 2026
- Maybank: 3-month compounded SORA and fixed home loan packages, checked 19 Oct 2026 maybank2u.com.sg, checked 8 November 2026
- OCBC: Home loan for HDB and private home, checked 19 Oct 2026 ocbc.com, checked 8 November 2026
- Standard Chartered: 3M compounded SORA package, checked 19 Oct 2026 sc.com, checked 8 November 2026
- DBS: Home loan rates online, checked 19 Oct 2026 dbs.com.sg, checked 8 November 2026
- HSBC: Home loans (Premier rate from 1.54% for loans of S$900,000 or more), checked 19 Oct 2026 hsbc.com.sg, checked 8 November 2026
- Redbrick: Compare home loans in Singapore (rate ranges, 5 Oct 2026), checked 19 Oct 2026 redbrick.sg, checked 8 November 2026
Fact-checked against HDB, IRAS, CPF, MAS.
