On this page
Key takeaways
- 100% of the lower of price and valuation is the most CPF can pay for a resale flat, if the lease covers the youngest buyer to 95.
- 90% of that limit is what buyers get when the lease only covers them to age 90, and 70% when it reaches 80.
- S$20,000 per buyer is the most you can keep in your OA when taking an HDB loan; the rest goes into the flat first.
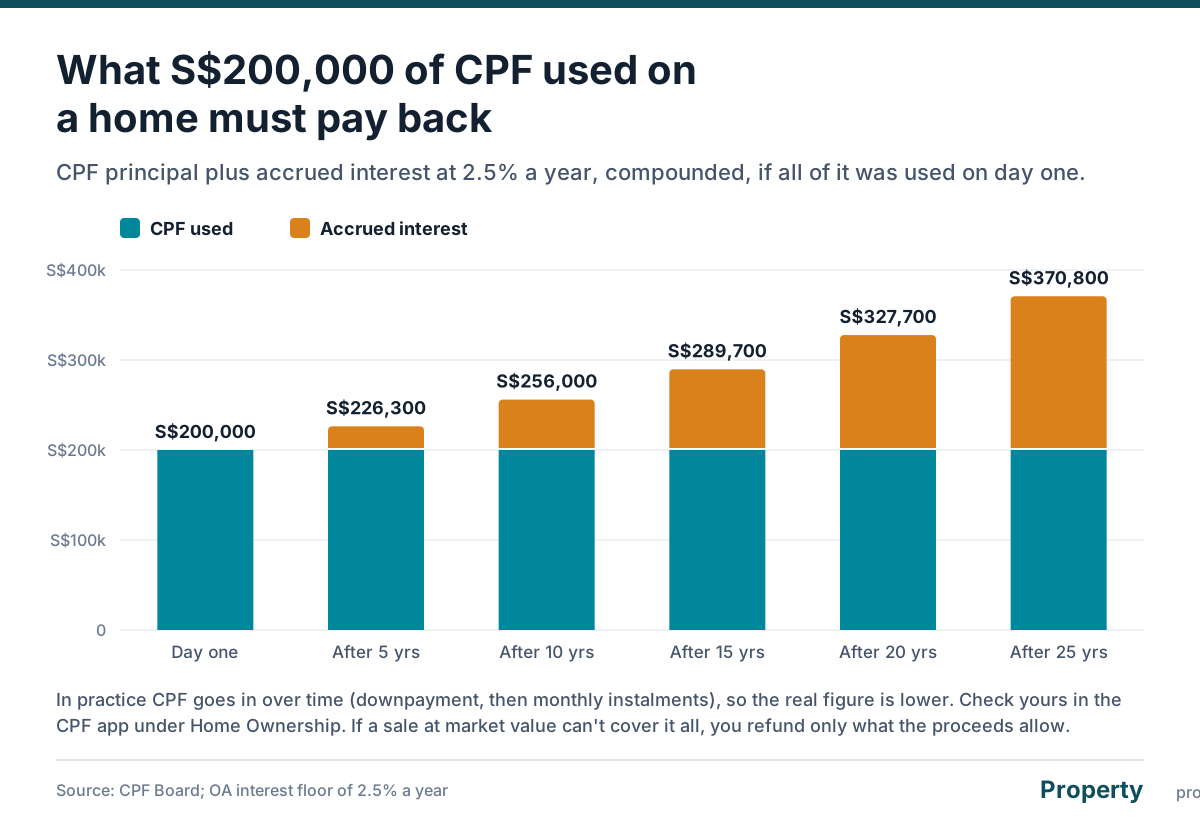
- 2.5% a year accrued interest is added to every CPF dollar used, and is refunded to your own CPF when you sell.
The numbers
- Downpayment (HDB loan)
- 25% of price or valuation, all of it payable from CPF OA
- Valuation Limit
- Lower of resale price and valuation at purchase
- Lease rule
- Full use if lease covers youngest buyer to 95; pro-rated if not; 20 years minimum
- Must be cash
- Option fee, exercise fee, cash over valuation
- OA you can keep
- Up to S$20,000 per buyer with an HDB loan
How this works in practice
With an HDB loan, you can use your CPF Ordinary Account (OA) for the whole 25% downpayment and for your monthly instalments, up to the Valuation Limit: the lower of the resale price and HDB’s valuation. That full limit applies only if the flat’s remaining lease covers the youngest buyer to age 95. If it doesn’t, the limit is pro-rated. OA can also pay stamp duty and legal fees. The option fee, exercise fee and any cash over valuation must be cash. We checked these rules against CPF Board and HDB pages on 14 October 2026.
What CPF can pay for on an HDB flat
| Cost | HDB loan | Bank loan |
|---|---|---|
| Option fee and exercise fee (up to S$5,000) | Cash | Cash |
| Rest of the 25% downpayment | OA or cash | At least 5% cash, rest OA or cash |
| Cash over valuation | Cash | Cash |
| Monthly instalments | OA or cash | OA or cash |
| Buyer’s Stamp Duty and legal fees | OA or cash | OA or cash |
| Service and conservancy charges | Cash | Cash |
Stamp duty is due to IRAS within 14 days. For a completed resale flat, you usually pay it in cash and CPF reimburses you on the completion date.
The Valuation Limit
The Valuation Limit (VL) is the lower of the price you pay and the valuation at purchase. It caps the CPF that all the owners together can put into the flat, counting the downpayment and every instalment paid from OA, interest included.
If you pay above valuation, the gap is cash and CPF never covers it. Our HDB valuation and COV page explains why that matters.
When your CPF use reaches the VL, what happens next depends on your loan:
| Loan | After the VL is reached |
|---|---|
| HDB loan, resale flat | OA can keep paying the loan only if you have set aside the BRS |
| Bank loan | OA can go up to 120% of VL, the Withdrawal Limit, if you have set aside the BRS |
| New flat bought from HDB, HDB loan | OA can pay the full purchase price, including the loan |
The Basic Retirement Sum (BRS) is S$110,200 in 2026 and S$114,100 in 2027. If you are below 55, the current year’s figure applies.
The age-95 lease rule
You can use CPF up to the full VL only if the flat’s remaining lease covers the youngest buyer to age 95. Add the youngest buyer’s age to the lease left: if the total is 95 or more, you’re fine. If not, CPF use is pro-rated, and the flat needs at least 20 years of lease left for any CPF use.
| Lease covers youngest buyer to | CPF usable | HDB loan limit |
|---|---|---|
| Age 95 or beyond | 100% of VL | 75% of VL |
| Age 90 | 90% of VL | About 67.5% |
| Age 80 | 70% of VL | About 52.5% |
The CPF percentages come from CPF’s and MND’s own examples; the loan limits apply the same pro-rating to HDB’s 75% cap. That 75% loan-to-value cap has applied to HDB loans since 20 August 2024. CPF’s own example: two 25-year-olds buying a S$550,000 flat with 65 years left can use up to S$495,000, or 90%. The HDB loan calculator uses both the 75% cap and the age-95 pro-rate.
How much OA you keep with an HDB loan
HDB lets each buyer keep up to S$20,000 in their OA. Everything above that goes into the flat before HDB lends you anything. CPF suggests keeping that S$20,000 as a buffer for instalments if your income stops for a while. With a bank loan there’s no such rule, so you choose how much OA to use.
Worked example: a S$600,000 resale flat
Wei Ming, 32, and Jasmine, 30, buy a 4-room resale flat for S$600,000. It values at the price and has 75 years of lease left, which covers Jasmine to 105. They have S$180,000 in their OAs together and take an HDB loan.
| Item | Amount |
|---|---|
| Valuation Limit | S$600,000 |
| OA kept back (S$20,000 each) | S$40,000 |
| OA put into the flat | S$140,000 |
| Downpayment, 25% | S$150,000 |
| Cash for the downpayment (includes S$5,000 option and exercise fees) | S$10,000 |
| HDB loan, 75% | S$450,000 |
| Buyer’s Stamp Duty | S$12,600 |
| Instalment, 25 years at 2.6% | About S$2,042 a month |
If they pay the stamp duty from CPF, their buffer drops from S$40,000 to about S$27,400.
Their CPF use starts at S$140,000. If they pay every instalment from OA, it reaches the S$600,000 VL after about 19 years. For the last 6 years of the loan, they can keep using OA only if they have set aside the BRS by then. Otherwise those instalments come from cash.
If they sell after 10 years, the first S$140,000 alone will have collected about S$39,200 in accrued interest at 2.5% a year. That S$179,200, plus every instalment paid from OA and its interest, goes back to their CPF before they get cash. Our CPF accrued interest guide shows the full refund.
Using less CPF on purpose
You don’t have to use the maximum. Paying part of the instalment in cash leaves more in your OA earning 2.5%, and cuts what you refund with interest when you sell. Test different splits in the HDB loan calculator, and if you’re weighing a bank loan, our downpayment calculator shows the 5% cash rule.
If you already own the flat, a refinance does not replace the purchase-time valuation with today’s market value. The dashboard is the usage figure. Paying the lender down is a partial repayment. Reserving Ordinary Account savings before 55 is a different form, covered in the mortgage checks before 55.
This page is general information from CPF Board, HDB and MND. CPF’s housing usage calculator gives the exact limit for your ages and lease.
Questions on this topic
Can I use CPF for the whole HDB downpayment?
Yes, with an HDB loan. CPF says OA savings can pay the downpayment and the rest of the price. The option fee and exercise fee, up to S$5,000, must be paid in cash first, and they count towards the price.
What is the CPF Valuation Limit for an HDB flat?
The lower of the resale price and HDB's valuation at the time you buy. If you pay S$620,000 for a flat valued at S$600,000, CPF counts only S$600,000 and the S$20,000 cash over valuation must be paid in cash.
What happens when I hit the Valuation Limit?
For a resale flat with an HDB loan, you can keep paying instalments from OA only if you have set aside the Basic Retirement Sum, S$110,200 for members below 55 in 2026. Otherwise the remaining instalments are paid in cash.
How does the remaining lease affect CPF use?
If the lease covers the youngest buyer to age 95, you can use CPF up to the full Valuation Limit. If not, the amount is pro-rated, and the flat needs at least 20 years of lease left for any CPF use. CPF's example: two 25-year-olds buying a flat with 65 years left can use 90% of the price.
Can I use CPF to pay stamp duty and legal fees?
Yes. CPF says OA savings can pay stamp duty and legal fees in full. Stamp duty is due within 14 days, so for a resale flat you usually pay in cash first and CPF reimburses you at completion.
Do I have to use all my CPF if I take an HDB loan?
Nearly. HDB lets each buyer keep up to S$20,000 in their OA. The rest goes into the flat before HDB lends. With a bank loan there is no such rule, but at least 5% of the price must be cash.
Get a personalised Singapore shortlist and financing check
Share your budget and what you're comparing. We'll reply on WhatsApp with matching units, recent caveats and your exact cash/CPF breakdown.
Sources
Facts on this page were checked against these sources on 8 November 2026.
- CPF: How much CPF savings you can use for your home purchase (updated May 2026) cpf.gov.sg, checked 8 November 2026
- CPF: CPF usage when the lease covers the youngest buyer to age 95 cpf.gov.sg, checked 8 November 2026
- CPF: Using CPF when the lease doesn't cover the youngest buyer to age 95 (updated July 2026) cpf.gov.sg, checked 8 November 2026
- MND: Worked examples of CPF use and HDB loans for older flats (2019) mnd.gov.sg, checked 8 November 2026
- CPF: Can I use my CPF savings for the down payment of my property? cpf.gov.sg, checked 8 November 2026
- CPF: HDB option fee and housing expenses you should know (April 2026) cpf.gov.sg, checked 8 November 2026
- CPF: Which property-related fees can I use my CPF savings for? cpf.gov.sg, checked 8 November 2026
- CPF: Using your CPF to buy a home (keeping S$20,000 in OA) cpf.gov.sg, checked 8 November 2026
- HDB: Housing loan from HDB (LTV, CPF retention, tenure) hdb.gov.sg, checked 8 November 2026
- CPF: How much is my Basic Retirement Sum? cpf.gov.sg, checked 8 November 2026
- CPF: 4% floor extended to end-2027; OA rate 2.5% for October to December 2026 cpf.gov.sg, checked 8 November 2026
Fact-checked against HDB, IRAS, CPF, MAS.
