At a glance
- Income ceiling
- S$16,000 a month; S$18,000 for new units in ECs whose land tender closed on or after 24 Aug 2026
- Who can apply
- A Singapore citizen with at least one other citizen or PR in a family nucleus, or 2 to 4 citizen singles aged 35 and up
- MOP
- 5 years for current and grandfathered ECs; 10 years (privatised after 15) for land tendered from 8 May 2026
- Loan limit
- Mortgage Servicing Ratio caps the repayment at 30% of income, tested at 4%
- Grant
- CPF Housing Grant of up to S$30,000 for first-timer citizen couples earning up to S$10,000
The short answer
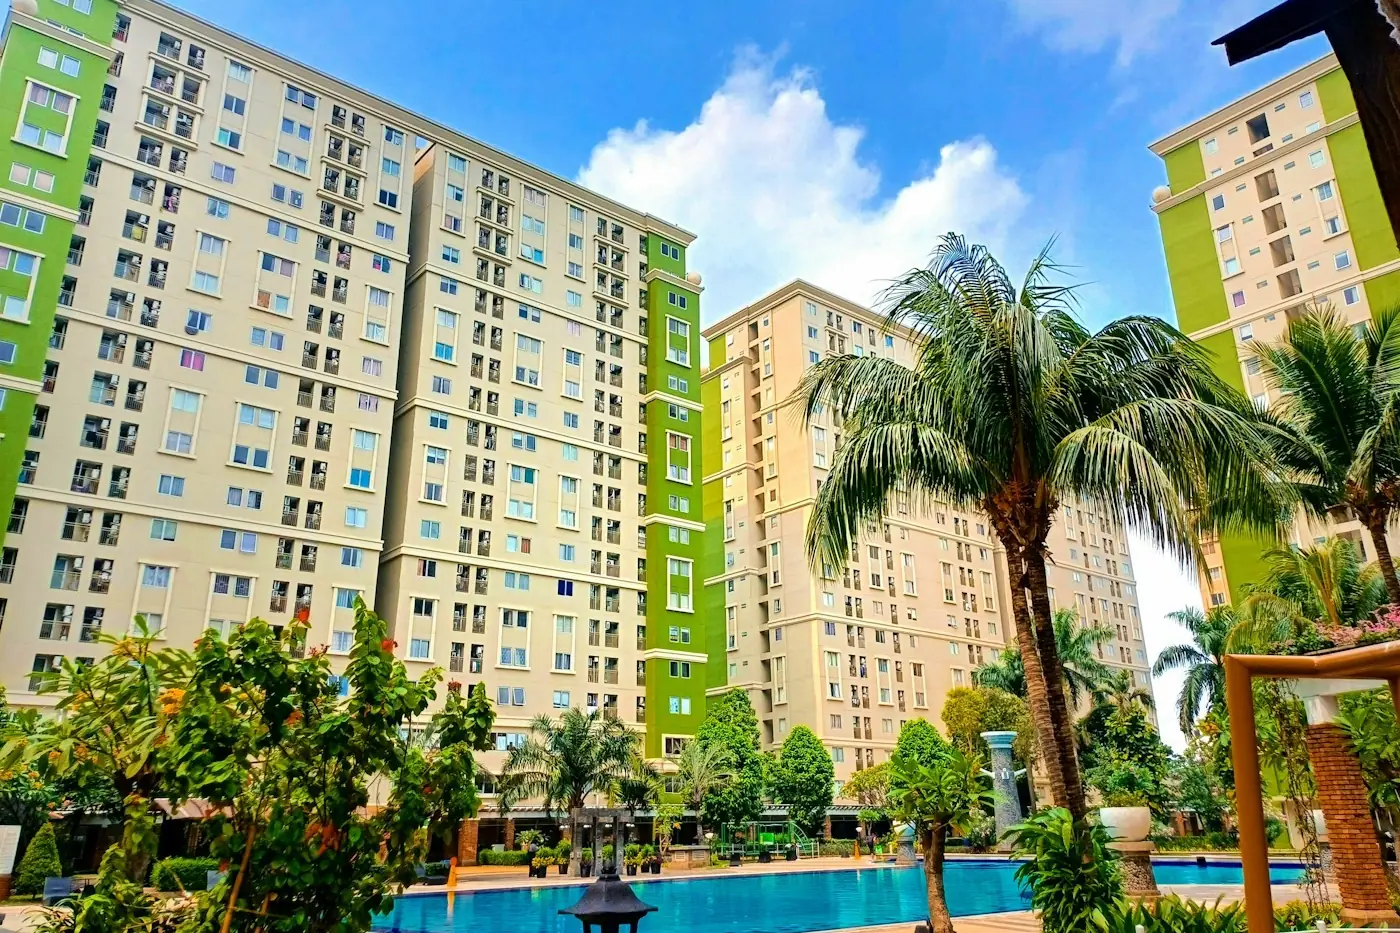
An executive condominium (EC) is a condo with pools, gyms and full facilities, built and sold by a private developer on land the government sells for that purpose. It costs less than a private condo nearby, but you have to qualify to buy one new, and you cannot sell it for the first few years.
In October 2026 the main rules are:
- At least one buyer must be a Singapore citizen, applying with family or with other citizen singles.
- Household income must be S$16,000 a month or less. ECs on land tendered from 24 August 2026 will allow up to S$18,000.
- You cannot own private property, or have sold one in the past 30 months.
- If you own an HDB flat, you must sell it within 6 months after completing the EC purchase.
- The mortgage repayment cannot exceed 30% of your income.
- Every EC on sale today has a 5-year MOP. ECs on land tendered from 8 May 2026 will have a 10-year MOP.
The rest of this guide goes through each rule, then works through what a S$1.65 million EC costs a couple earning S$15,000. If you are deciding between an EC and a private condo, read our EC vs condo comparison next.
What an EC is
ECs sit between HDB flats and private condos. The government sells EC sites through its land sales programme, with HDB running the tenders as the land sales agent. A developer wins the tender, builds the project and sells the units directly to buyers, much like a private launch.
What makes it different from a condo is the set of HDB conditions attached to buying new: the eligibility rules, the income ceiling, the Mortgage Servicing Ratio and the minimum occupation period. Once the EC is fully privatised, those restrictions fall away and it is treated like any other private condo.
Prices reflect the conditions. PropNex data quoted by EdgeProp put the median price of new ECs sold in the first quarter of 2026 at S$1,837 psf, about 27% below the S$2,503 psf median for new 99-year leasehold condos in the Outside Central Region.
EC eligibility
These are HDB’s conditions for buying a new EC from the developer.
| Condition | Rule |
|---|---|
| Citizenship | You must be a Singapore citizen, with at least one other citizen or PR in the application. Singles applying together must all be citizens. |
| Household | Fiancé and fiancée, married couple with or without children, parents and siblings, widowed or divorced parent with children, orphaned siblings, or 2 to 4 singles applying jointly |
| Age | At least 21. Singles applying jointly must each be at least 35. |
| Income | Total household income of S$16,000 a month or less (S$18,000 for new units on land tendered from 24 Aug 2026) |
| Private property | No one listed can own or have an interest in private residential property in Singapore or overseas, or have disposed of one in the last 30 months |
| HDB flat | Allowed, but it must be disposed of within 6 months after completing the EC purchase |
| Past subsidies | Taken one housing subsidy: you are a second-timer and may pay a resale levy. Taken two: you cannot buy. |
The core members you list must stay on the application and live in the EC throughout the MOP.
Owning one non-residential property, such as a shop unit, is allowed for EC land sales launched on or after 9 May 2023. Anyone with more must have sold the others at least 30 months before applying.
The EC income ceiling: S$16,000 or S$18,000
At the National Day Rally on 23 August 2026, the government raised the EC income ceiling from S$16,000 to S$18,000. The catch is the start date. The higher ceiling only applies to new units in EC projects where the land sale tender closes on or after 24 August 2026.
That means S$16,000 still applies to:
- balance units in ECs already on sale, according to MND
- the upcoming EC launches at Senja Close, Woodlands Drive 17 and Sembawang Road, whose land was sold before the cut-off
The first site under the S$18,000 ceiling is Canberra Drive, whose tender closed on 1 October 2026. ERA expects the first ECs under the newer rules to reach the market about 1.5 to 2 years after the May 2026 changes, so S$18,000 units are not on sale yet.
Income is the gross monthly income of everyone listed on the application, not just the two main buyers. Use our HDB grant calculator to check your average household income before you book.
The May 2026 EC rule changes
On 8 May 2026 the Ministry of National Development tightened the EC scheme. The changes apply to EC land sites whose tenders close on or after 8 May 2026.
| ECs on land tendered before 8 May 2026 | ECs on land tendered from 8 May 2026 | |
|---|---|---|
| Minimum occupation period | 5 years | 10 years |
| Who you can sell to after the MOP | Citizens and PRs | Citizens and PRs |
| Full privatisation (open to foreigners) | After 10 years | After 15 years |
| Deferred Payment Scheme | Developer may offer it | Removed |
| Share of units for first-timers | 70% | 90%, with a two-year priority period |
PropNex counts five upcoming EC projects, about 1,970 units in total, that keep the old rules. The first site sold under the new rules is Canberra Drive, which drew 13 bids and a record EC land price of S$825 psf ppr when its tender closed on 1 October 2026.
EC MOP and resale rules
The minimum occupation period runs from the date the EC gets its Temporary Occupation Permit, not from the day you book.
Under the rules that cover every EC on sale today:
- Years 1 to 5. You must live in the unit. You cannot sell it.
- After year 5. You can sell, but only to Singapore citizens and PRs.
- After year 10. The EC is fully privatised. You can sell to anyone, including foreigners and companies.
For ECs on land tendered from 8 May 2026, the same steps happen at year 10 and year 15.
The Mortgage Servicing Ratio only applies while an EC is within its MOP. Anyone buying a resale EC after that is tested on TDSR alone, like a condo buyer.
CPF Housing Grant for ECs
First-timer families buying a new EC from the developer can get a CPF Housing Grant, credited to their CPF Ordinary Account. The amount depends on average monthly household income.
| Household income | Citizen couple, both first-timers | Citizen and PR couple | Citizen first-timer and second-timer couple |
|---|---|---|---|
| Up to S$10,000 | S$30,000 | S$20,000 | S$15,000 |
| S$10,001 to S$11,000 | S$20,000 | S$10,000 | S$10,000 |
| S$11,001 to S$12,000 | S$10,000 | Nil | S$5,000 |
| Above S$12,000 | Nil | Nil | Nil |
The grant has to be refunded to your CPF account, with accrued interest, when you sell. The bands stop at S$12,000, so most households near the S$16,000 or S$18,000 ceiling get no EC grant. None of the 2026 announcements we reviewed changed these amounts.
Loans: MSR, TDSR and the Deferred Payment Scheme
ECs are financed with bank loans. Three limits apply.
| Test | Limit |
|---|---|
| Mortgage Servicing Ratio (MSR) | Home loan repayment up to 30% of gross monthly income, for ECs still within their MOP |
| Total Debt Servicing Ratio (TDSR) | All debt repayments up to 55% of gross monthly income |
| Loan-to-value | Up to 75% of the price if you have no other housing loan and the tenure is 30 years or less and ends by age 65 |
Banks work out both ratios using a 4% interest rate floor set by MAS, even when actual rates are lower. For most EC buyers the MSR is the binding limit, as the worked example below shows.
Deferred Payment Scheme. Under the DPS, you pay 20% of the price upfront (a 5% booking fee in cash and 15% within 8 weeks), then nothing more until the project gets its TOP, when the remaining 80% falls due. Your mortgage starts only then. PropNex estimates 60% to 70% or more of buyers in some projects chose it, and that DPS units usually cost 2% to 3% more.
The DPS has been removed for ECs on land tendered from 8 May 2026. Buyers of those projects pay in stages as the building goes up, like a private condo. The five grandfathered projects can still offer it.
ABSD on an EC
The standard Additional Buyer’s Stamp Duty rates apply.
| Buyer | First home | Second home | Third and later |
|---|---|---|---|
| Singapore citizen | 0% | 20% | 30% |
| Singapore PR | 5% | 30% | 35% |
Most EC buyers own nothing else, so they pay no ABSD. If you are a married couple with at least one citizen and you still own an HDB flat, MOF says couples buying a new EC get the ABSD remission upfront, because HDB already requires them to sell the flat. A couple buying a private condo while owning a flat has to pay the 20% first and claim it back after selling.
Buyer’s stamp duty is payable on every purchase. Our stamp duty calculator works it out for any price.
EC launches in 2026 and what is coming
Launched in 2026
| Project | Location | Launch | Result |
|---|---|---|---|
| Coastal Cabana | Jalan Loyang Besar, Pasir Ris | 17 to 18 Jan 2026 | 67% of 748 units sold on launch weekend at an average S$1,734 psf |
| Rivelle Tampines | Opposite Tampines West MRT | March 2026 | All 572 units sold within about a month |
Upcoming, under the old rules (5-year MOP, DPS allowed, S$16,000 ceiling)
| Site | Area | Developer | Land price |
|---|---|---|---|
| Senja Close | Bukit Panjang, near Jelapang LRT | City Developments | S$771 psf ppr |
| Woodlands Drive 17 (first plot) | Woodlands South | City Developments | S$782 psf ppr |
| Woodlands Drive 17 (second plot) | Woodlands South | Sim Lian Group | S$794 psf ppr |
| Sembawang Road | Sembawang | Not confirmed in our sources | S$692 psf ppr |
| Miltonia Close | Yishun, beside Orchid Country Club | Hoi Hup Realty | S$732 psf ppr |
99.co expects these to launch from the second half of 2026 through 2027. Project names and prices were not announced when we checked.
Under the new rules (10-year MOP, no DPS, S$18,000 ceiling)
Canberra Drive, about 185 units. The top bid of S$825 psf ppr came from a consortium of Santarli Realty, Heeton Holdings, Kay Lim Holdings and Sunray Group Holdings, and PropNex expects an average selling price of around S$1,900 psf. SRI also lists Admiralty Walk, with a tender closing in December 2026.
Worked example: a S$1.65 million EC on a S$15,000 income
Assumptions (yours will differ): a married couple, both Singapore citizens and first-timers, with a combined gross income of S$15,000 a month and no other debts. They buy a 900 sq ft three-bedroom at about S$1,833 psf, close to the first-quarter 2026 median, for S$1.65 million. No grant, because their income is above S$12,000. 30-year loan.
Step 1: the loan limit
| Limit | Calculation | Maximum loan |
|---|---|---|
| Loan-to-value 75% | 75% of S$1,650,000 | S$1,237,500 |
| MSR 30% at 4% | S$4,500 a month over 30 years | about S$942,600 |
| Loan they can get | the lower of the two | about S$942,600 |
The MSR wins. Their loan is about 57% of the price, not 75%.
Step 2: what they need upfront
| Item | Amount |
|---|---|
| Price | S$1,650,000 |
| Bank loan | S$942,600 |
| Down payment from CPF and cash | S$707,400 |
| of which cash minimum (5% of price) | S$82,500 |
| Buyer’s stamp duty | S$52,100 |
| ABSD | Nil (first home) |
| Total before legal fees | S$759,500 |
Buyer’s stamp duty on S$1.65 million is 1% on the first S$180,000, 2% on the next S$180,000, 3% on the next S$640,000, 4% on the next S$500,000 and 5% on the last S$150,000.
What changes the picture
- A higher income. At S$16,000 the MSR loan rises to about S$1,005,400. At S$18,000, which only applies to ECs on land tendered from 24 August 2026, it is about S$1,131,100, cutting the down payment to about S$518,900.
- Selling an HDB flat. Upgraders usually fund the gap with their flat’s sale proceeds and the CPF refunded to their accounts. Our HDB to condo upgrading guide shows how those numbers work.
- The DPS. On a grandfathered launch with the DPS, the couple pays 20% (S$330,000) at the start, but the rest of the down payment is still due at TOP, because the loan is capped by MSR either way.
Try other prices and incomes in our mortgage calculator.
Before you book
- Work out your household income the way HDB does, including everyone on the application.
- Get an in-principle loan approval so you know your MSR limit in writing.
- Check whether the project is on the old rules or the new ones. It changes your MOP, your payment schedule and when you can sell to foreigners.
- If you own an HDB flat, plan the sale so it completes within 6 months after your EC purchase completes.
Common questions
What is the EC income ceiling in 2026?
S$16,000 a month for the household. From the 2026 National Day Rally, new units in ECs whose land tender closed on or after 24 August 2026 have a S$18,000 ceiling. Balance units in existing ECs and the upcoming Senja Close, Woodlands Drive 17 and Sembawang Road launches stay at S$16,000.
Can I buy an EC if I own an HDB flat?
Yes, as long as you have not already taken two housing subsidies. You must dispose of the flat within 6 months after completing the EC purchase. If you bought the flat from HDB or with a grant, you are a second-timer and may pay a resale levy.
What is the MOP for an EC?
It depends on when the land was sold. ECs on land tendered before 8 May 2026 have a 5-year MOP, can be sold to citizens and PRs after that, and become fully private after 10 years. ECs on land tendered from 8 May 2026 have a 10-year MOP and are privatised after 15 years.
Can I buy an EC if I own private property?
Not straight away. No one in the application can own a private residential property, in Singapore or overseas, and anyone who sold one must wait 30 months from the legal completion of the sale before applying.
Is the Deferred Payment Scheme still available for ECs?
Only for the last batch of ECs under the old rules. The scheme was removed for ECs on land tendered from 8 May 2026, starting with the Canberra Drive site. Developers of the five grandfathered projects can still offer it.
How much do I need to earn to buy a S$1.65 million EC?
Under the 30% MSR tested at 4%, an income of S$15,000 supports a 30-year loan of about S$943,000. That leaves about S$707,000 to pay from CPF and cash, plus S$52,100 in buyer's stamp duty. A household at S$18,000 could borrow about S$1.13 million.
Get a free valuation
Tell us your block and flat type. We'll send recent prices for your block and nearby blocks, and what a sale would leave you after your loan and CPF refund.
Sources
Facts on this page were checked against these sources on 13 October 2026.
- HDB: Executive condominium eligibility
- EdgeProp: Income ceilings reset to S$16,000 for BTO and S$18,000 for ECs (23 Aug 2026)
- Stacked Homes: HDB raises income ceiling to S$16k and EC ceiling to S$18k
- EdgeProp: Government tightens EC rules with 10-year MOP and DPS removal (8 May 2026)
- ERA: Commentary on new EC policy changes (8 May 2026)
- PropNex: Key changes to the EC housing scheme (8 May 2026)
- 99.co: Five upcoming EC launches with the Deferred Payment Scheme
- Stacked Homes: The last 5-year MOP ECs and where they will launch (22 May 2026)
- EdgeProp: Canberra Drive EC site sets record land price of S$825 psf ppr (1 Oct 2026)
- EdgeProp: Rivelle Tampines fully sold within a month (25 Apr 2026)
- EdgeProp: Coastal Cabana EC moves 67% of units at S$1,734 psf (18 Jan 2026)
- PropertyGuru: CPF Housing Grant amounts, including for ECs
- MoneySense: Buying a property, how much can you afford (LTV, TDSR, MSR)
- MAS: Reply on TDSR medium-term interest rate floor of 4%
- MAS: Measures for a sustainable property market (ABSD rates, April 2023)
- MOF: Reply on upfront ABSD remission for married couples (new ECs and HDB flats)
- MOF: Buyer's Stamp Duty rates for higher-value properties
Read next
 Tool
BTO, Resale HDB, EC or Condo? Which Home Type Suits You Quiz
Seven taps check your eligibility for BTO, resale HDB, EC and condos under current HDB rules, then rank each option on your budget, timing and priorities.
GuideEC vs Condo in 2026: Price per Square Foot, Loans, Resale Rules and Gains Compared
EC vs private condo in 2026: the 27% price gap, MSR vs TDSR, MOP and resale limits, grants, ABSD and what ECs have made after privatisation, with a side-by-side example.
 Tool
HDB Grant Calculator 2026: EHG, Resale and EC Grants, and the New Income Ceilings
See which HDB grants you qualify for on a BTO, resale flat or new EC, how much each pays, and whether your income is within the ceilings raised in August 2026.
 Tool
Downpayment Calculator Singapore: Cash and CPF You Need for an HDB Flat or Condo
Work out the downpayment, cash minimum, COV, stamp duty and legal fees for an HDB flat, BTO, resale condo or new launch, and how much can come from CPF.
 Guide
Upgrading From HDB to Condo or EC in 2026: Order, Loans, ABSD and a Worked Example
How to upgrade from an HDB flat to a condo or EC in 2026: sell first or buy first, ABSD remission, the 6-month rules, 75% LTV, TDSR, MSR and a S$1.6m worked example.